Who killed the B2B software review industry and why?
43 months of data on the 5 sites that used to decide what software you bought - G2, Capterra, Software Advice, GetApp, TrustRadius - and the murder we all slept through.
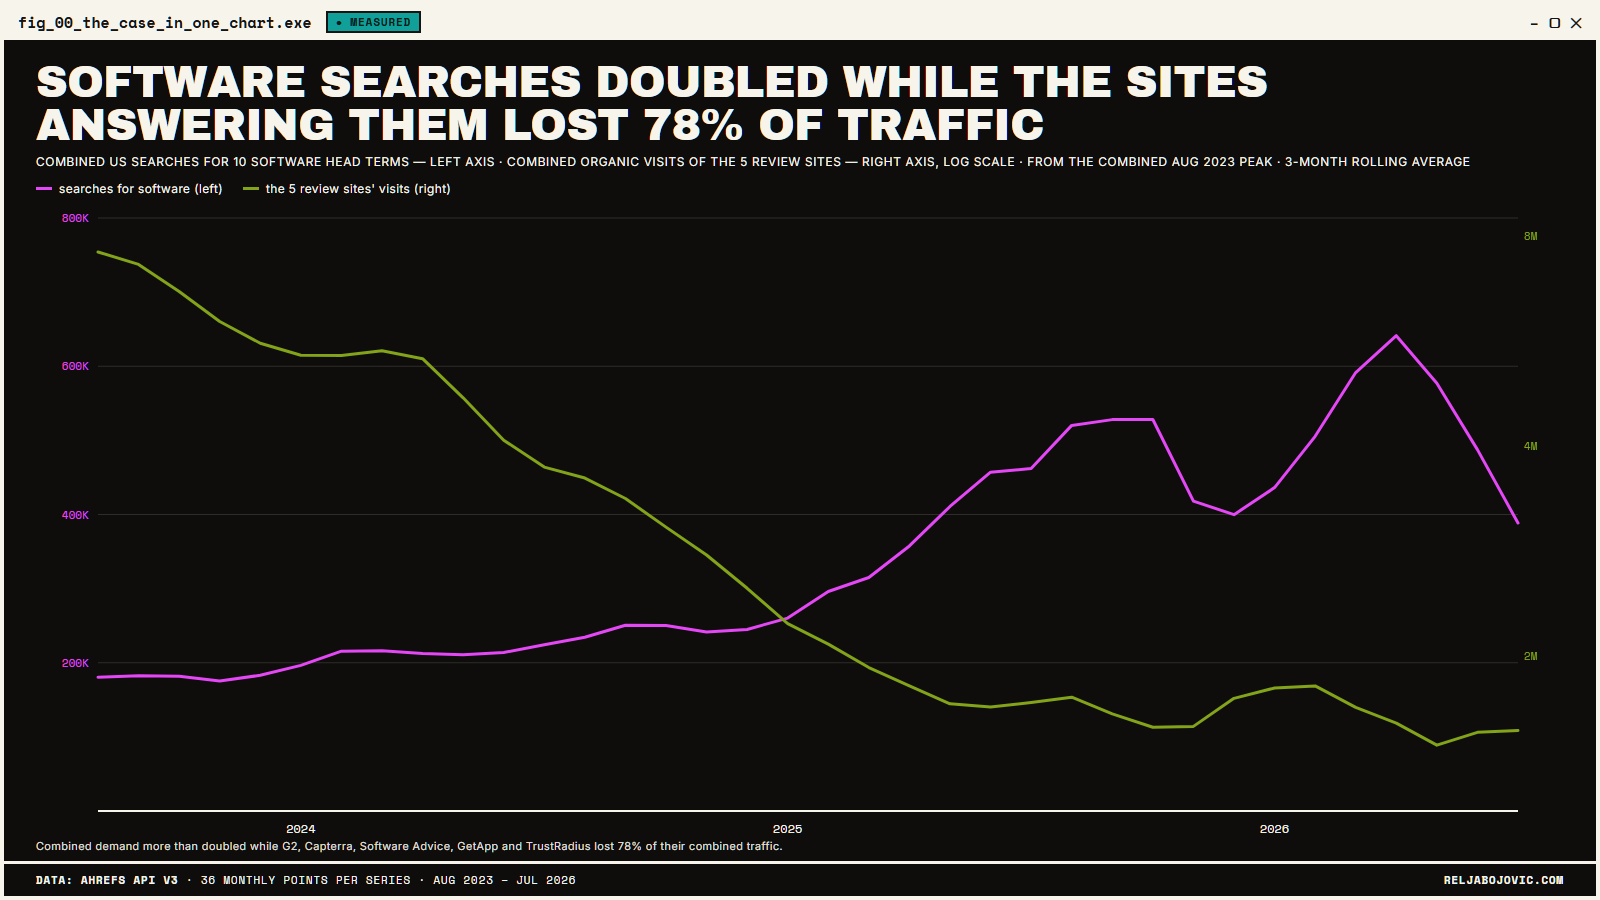
Ok, here’s a neat murder mystery for you: between 2023 and 2026, the entire B2B software review industry got wiped out in plain sight. To make things stranger, every suspect I can line up has an alibi.
Bad content? Nice try, but nope. The most earnest site in the category and the laziest template farm died the exact same death, -91% each.
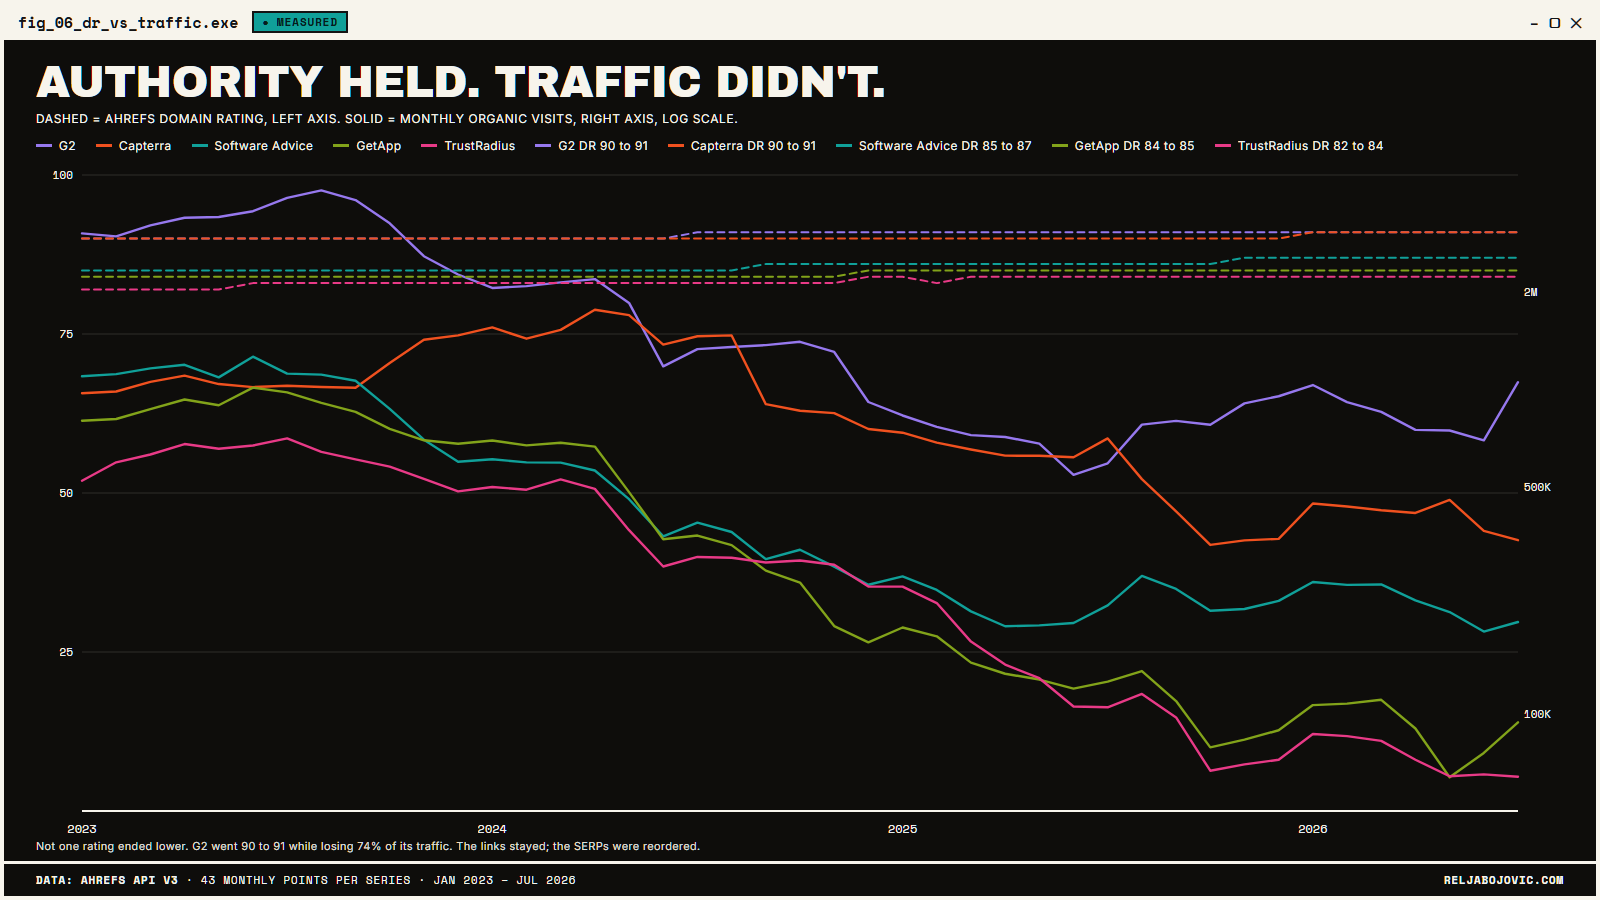
Links? Not quite, bubba. Every domain rating went UP while all 5 traffic charts drove off a cliff.
Buyers moved on? People googled these exact questions more every single year of the collapse.
5 sites, 5 different survival playbooks, 1 grave. And perhaps my favorite part: the lost traffic didn’t get redistributed. The sites that ‘won’ the vacated rankings collected just 1% of the traffic - the rest just stopped existing as clicks.
Disappearing acts like this aren’t exactly the most common thing, especially when FIVE different sites all hit the ground face-first. That’s why I’ll do my best Sherlock Holmes impersonation, with Ahrefs being my trusty Watson on this case.
Everything below comes from 43 months of Ahrefs data on all 5 sites, cross-checked against live US SERPs, SEC filings, public data, and the companies’ own press releases.
TL;DR
A short rundown of the facts, in case you get a feeling of existential dread when faced with a huge wall of text:
💥The collapse
- 5 sites - G2, Software Advice, Capterra, GetApp and TrustRadius - went from a combined 8.9M monthly organic visits at peak to about 1.75M in mid-2026 - an 80% wipeout that went unregistered in the DR department.
- Demand never left: 12 of 13 head terms in the niche are flat-to-up since 2023 (“crm software” +267%), and searches for “g2” itself grew 39% while g2.com lost 74% of its visits. People are asking for the referee by name and Google won’t put the call through.
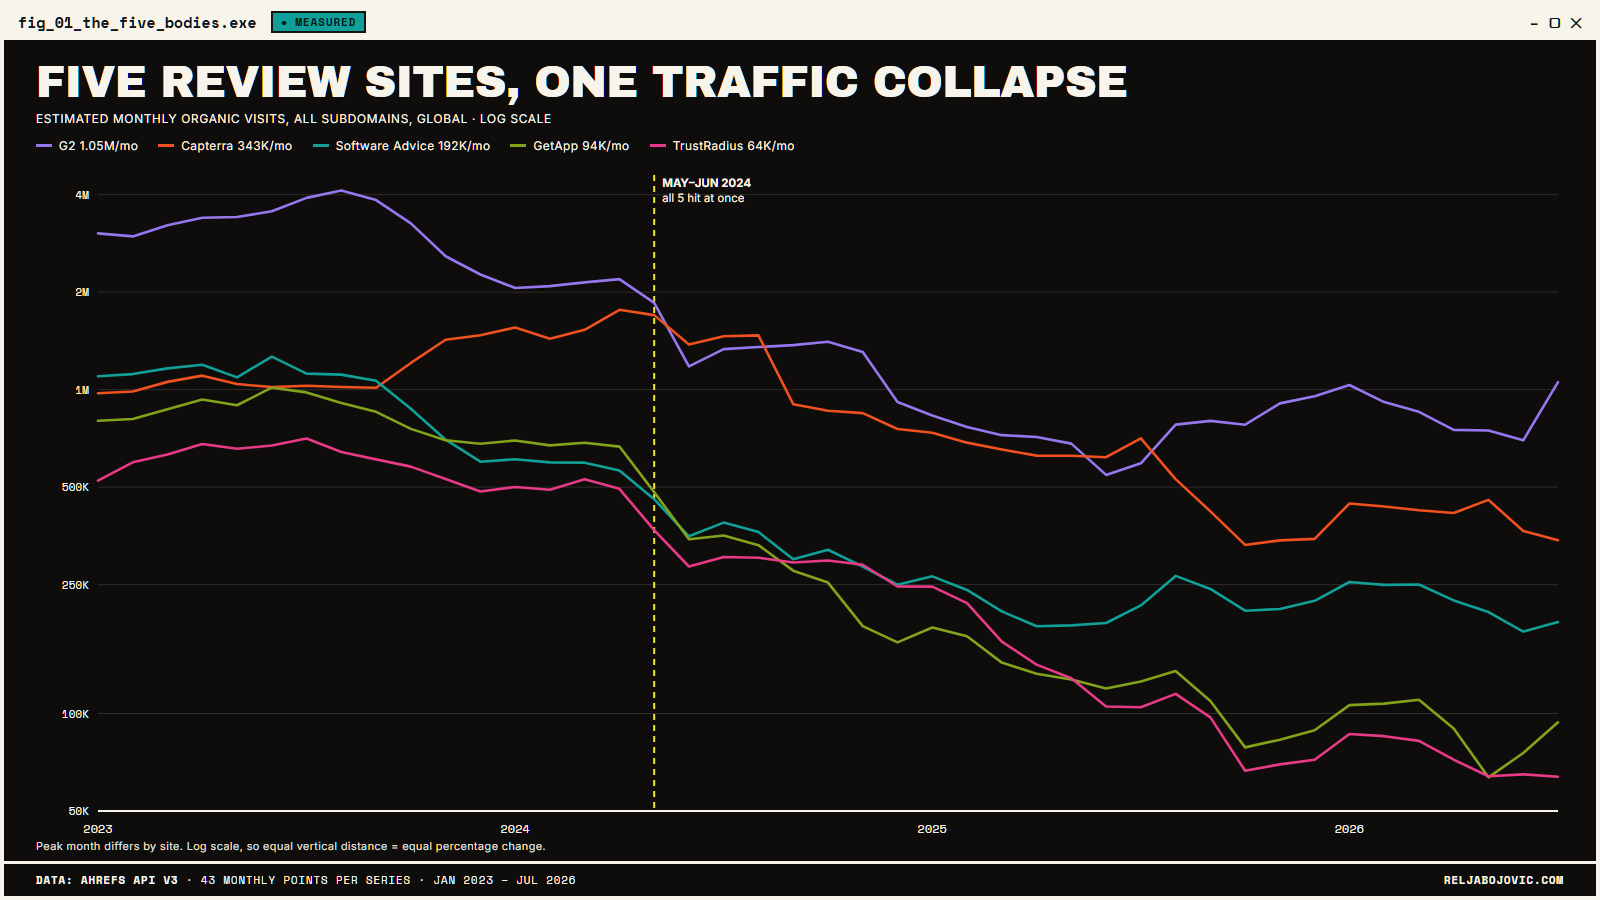
- May-June 2024 was a headshot fired at all 5 at once - top-3 keywords down 40-45% everywhere while positions 21-50 barely moved. The grouping is simply too tight to blame normal circumstances.
- Strategy changed nothing: the expander, rebuilder, pivoter, template farm and bystander all saw their traffic drop between -74% and -91%.
- The collapse ignored borders: capterra.fr lost 81% in a country that had no AI Overviews until July 2026. Whatever your favorite teardown blamed, France never got the murder weapon.
🔫The weapon
- 19 of G2’s 21 biggest surviving head keywords sit under an AI Overview, and all 19 lost the organic top 3. The 2 without an Overview kept theirs.
- AI Overviews didn’t use them as sources either: on their own money SERPs, the 5 sites lead the citation list once across 58 AI Overviews. Reddit leads 18 times. GetApp appears 0 times - on its own turf.
- Where there isn’t an AI Overview, the old economy still pays in full: “accounting software” and “project management software” are Overview-less, and the #1 blue links there collect 5 figures a month like it’s 2019.
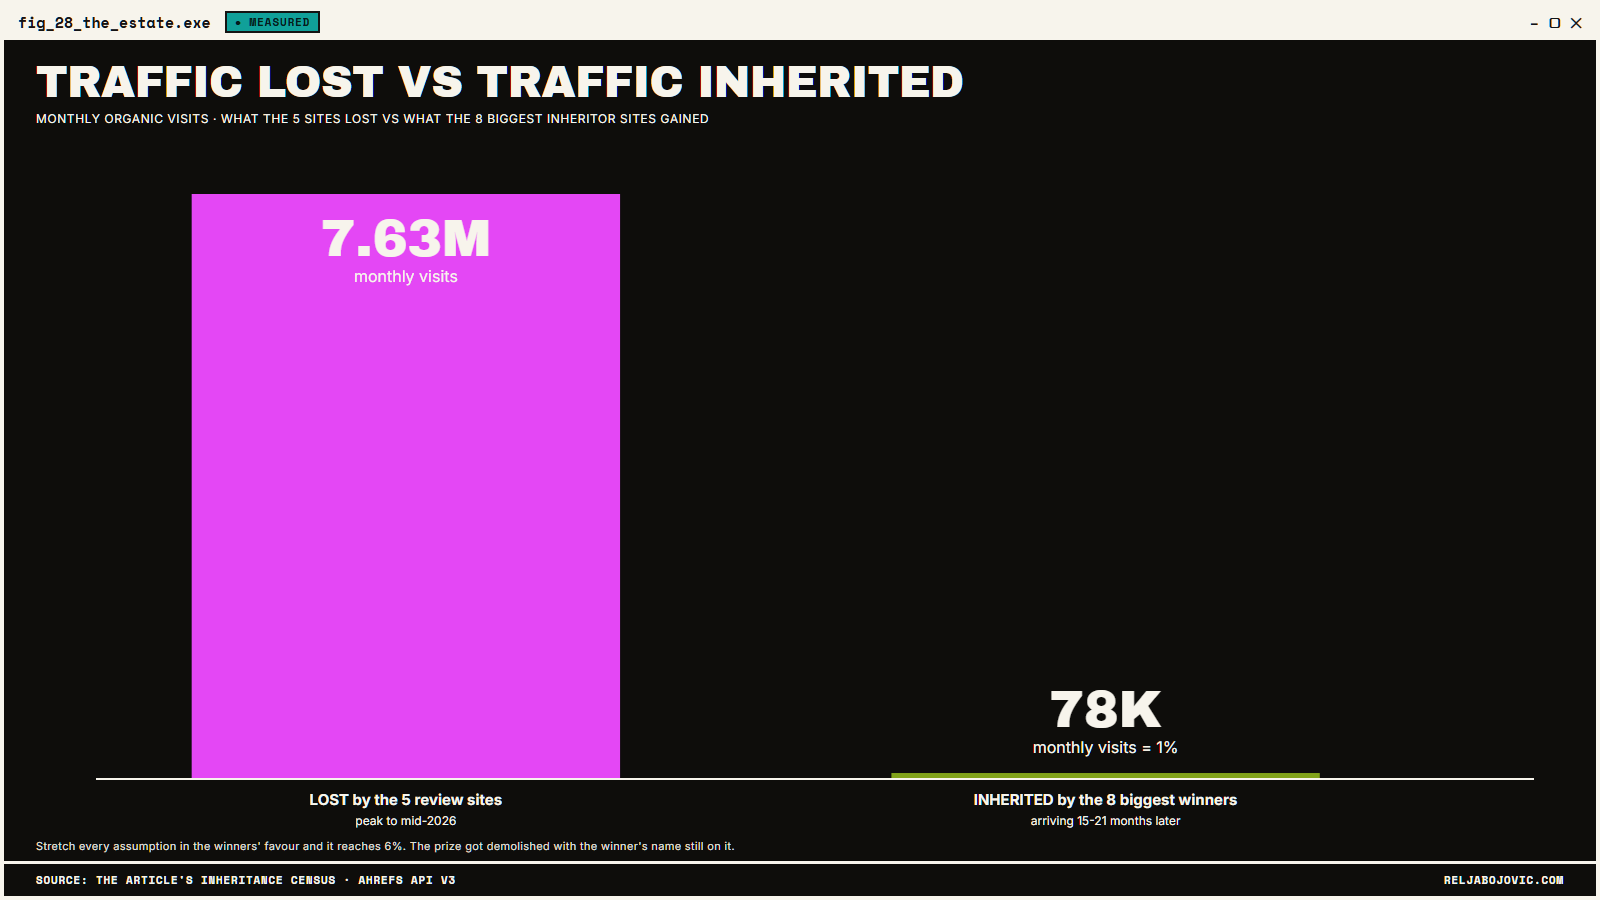
- The estate evaporated in probate: the “winners” of the vacated rankings collected 1-6% of the 7.6M lost monthly visits. Nobody outranked the review industry. The prize got demolished with the winner’s name still on it.
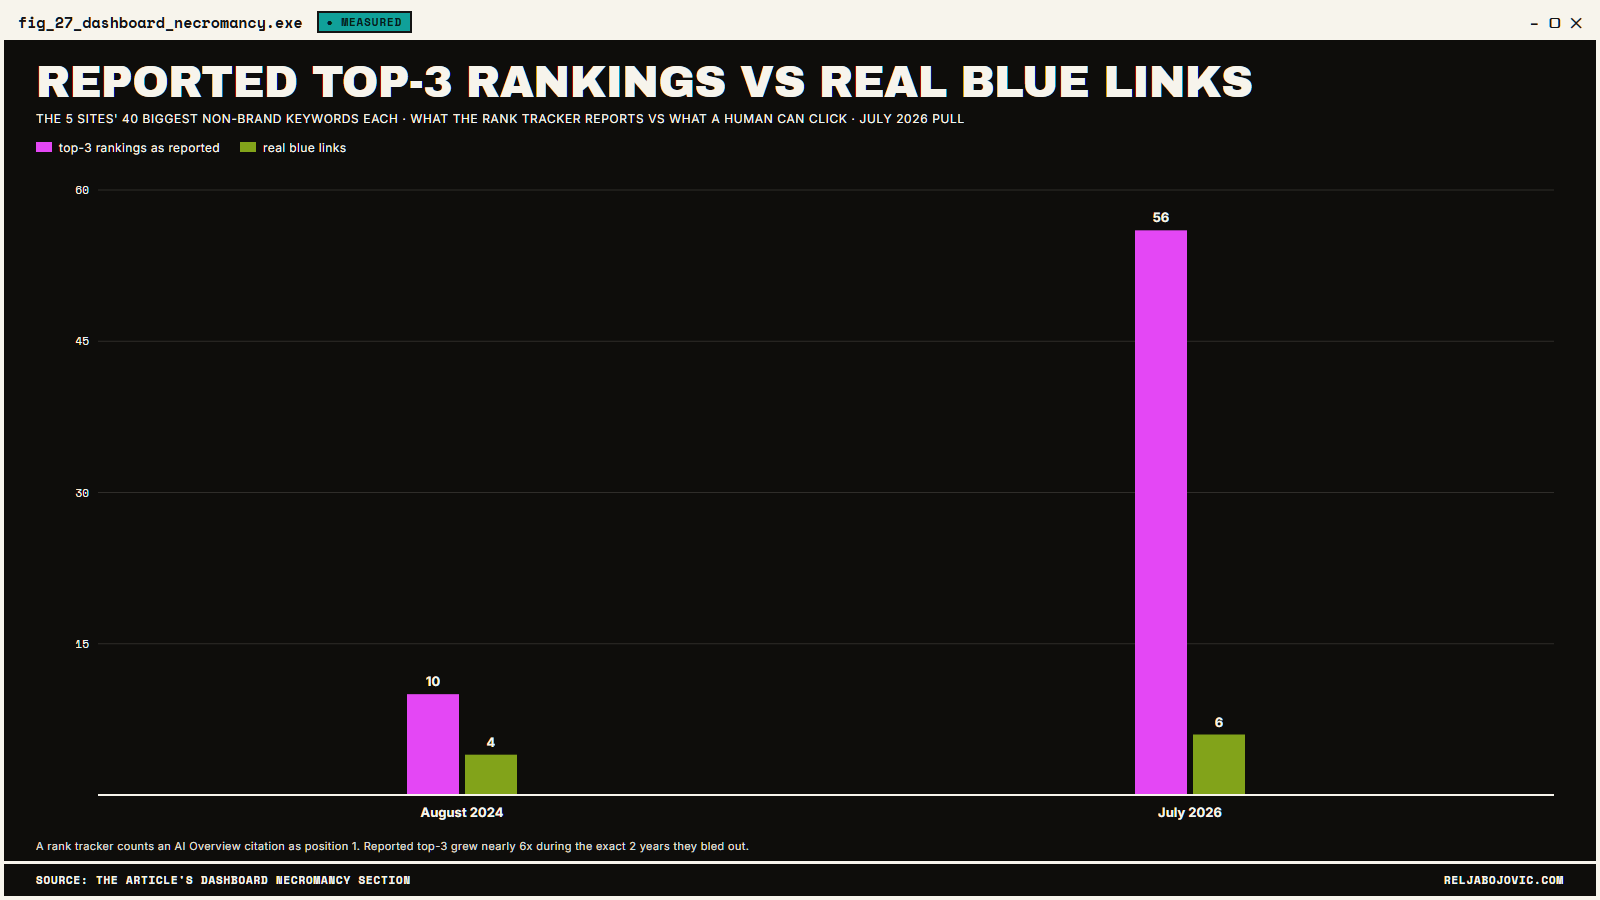
- The 5 sites’ reported top-3 count grew from 10 to 56 during the collapse while their real blue links went from 4 to 6, because rank trackers fold all of Google’s SERP features, including AI Overview citations into “position 1.”
💰The money
- Gartner’s 3 directories spent ~$22.2M on Google Ads buying back the traffic they used to get free. Contrastingly, TrustRadius spent $9 in 43 months and just gave up completely.
- LLMs still happily cite the corpses: ChatGPT cites G2 55,339 times, TrustRadius 16,351 times, and Google’s own answer boxes quote G2 12,000+ times while Google organic starved it.
- The market called it before the industry did: a $150M write-down, Gartner selling 3 whole brands to G2, and a mid-collapse exit press release that never says the word “traffic”. It seems like accountants ran the only honest dashboard in this story.
The crime scene
The 5 bodies
Long before I had Claude vomit out comparison tables, there was a simpler time. A time where we injected our verbal diarrhea straight into Google whenever we wanted to buy B2B software.
Capterra, Software Advice, and GetApp ran as “Gartner Digital Markets” for over a decade - hold that arrangement in mind; it doesn’t survive the story. Ironically, TrustRadius was the smallest and the most earnest, but they too were sold to HG Insights on June 19, 2025, mid-collapse.
Due to a lack of Gartner involvement, G2 was seen as the most independent of the five, but it wasn’t the complete truth. HubSpot, Salesforce and LinkedIn all owned shares in the review giant, which tells you how seriously anyone took the conflict of interest even before Google resolved it for them.
Their combined business was refereeing 1 question - which software should I buy? - and at its peak that business was worth roughly 8.9M organic visits a month.
| Site | Peak | Mid-2026 | Drop |
|---|---|---|---|
| G2 | 4.12M (Aug 2023) | 1.05M | -74% |
| Capterra | 1.76M (Apr 2024) | 343K | -81% |
| Software Advice | 1.26M (Jun 2023) | 192K | -85% |
| GetApp | 1.01M (Jun 2023) | 94K | -91% |
| TrustRadius | 707K (Jul 2023) | 64K | -91% |
Add the rows up: 8.9M a month at peak, about 1.75M by mid-2026. An entire industry lost 80% of its audience, and 4 of those 5 declines cleared 80%. With the way no one survived, the table almost looks like a Romanov family portrait.
The wipeout itself is already on the record - SE Ranking published all 5 declines side by side in January 2026, a few points off my numbers thanks to different windows and scopes. That study took the photograph. This one performs the autopsy, arrests the killers and finds out where the traffic actually went.
Don’t put on the tinfoil hats just yet
I know what you’re thinking - “Someone at Google woke up on the wrong side of the bed and decided to smite Gartner-owned brands because of a conflict of interest.” Whoa, hold your horses.
Gartner itself - the analyst business, the Magic Quadrants, the 5-figure seats - lost about 23% from its 2025 peak over the same window. The analysts survived while the affiliate arm got executed.
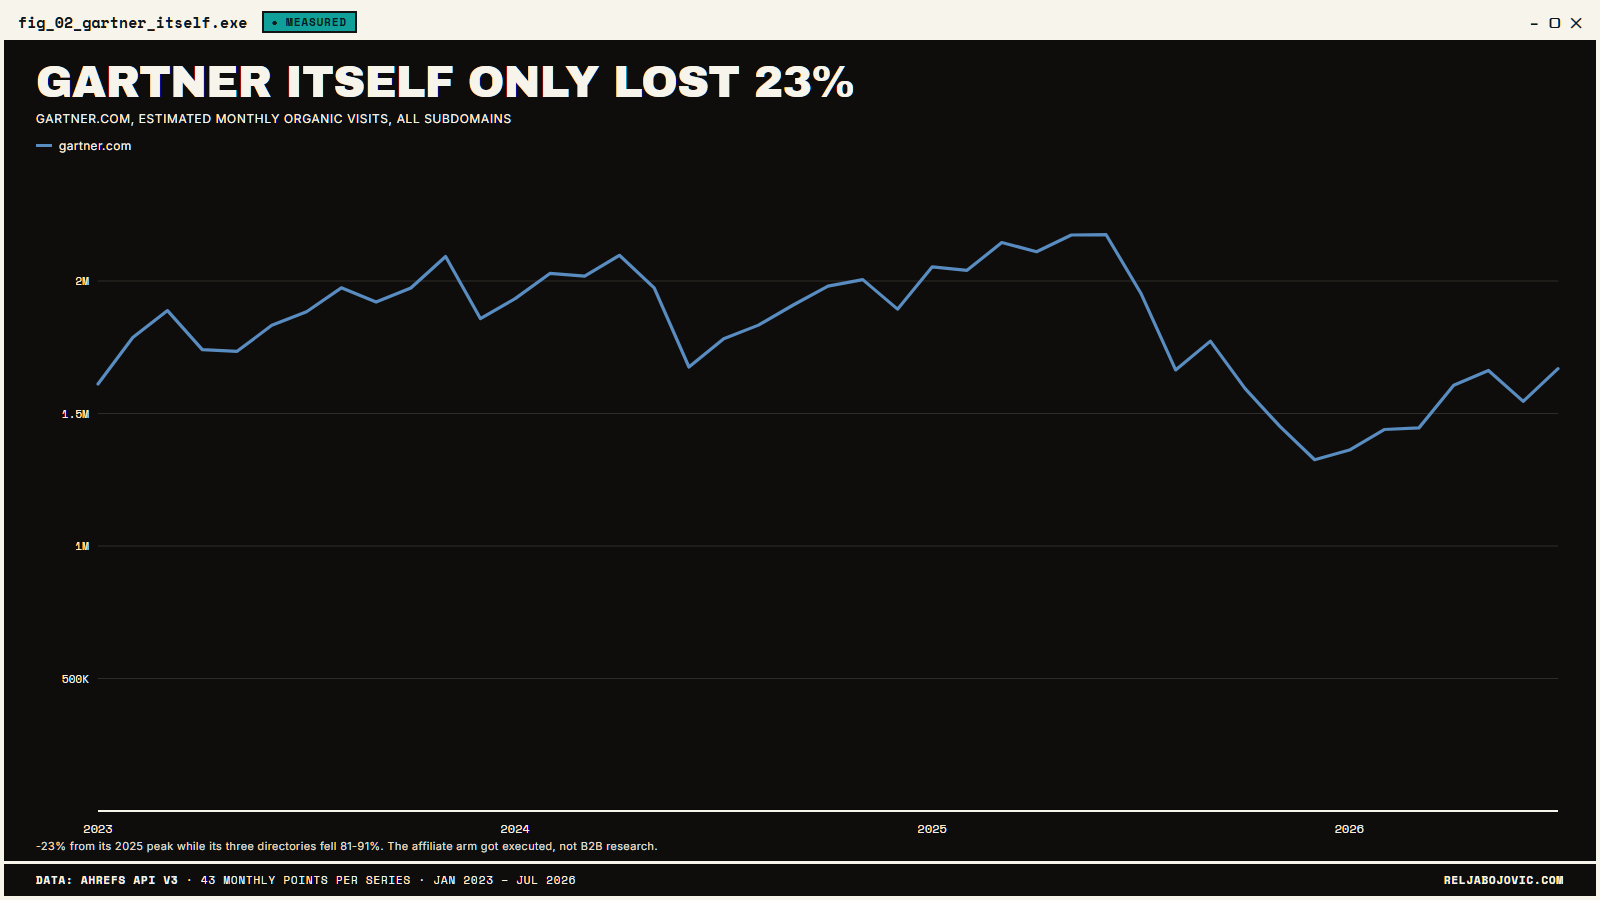
So spare me “B2B research died.” Something far more specific died, and Gartner - hold this thought for the money section - turns out to be the only actor in the entire story who saw the writing on the wall.
What it was worth
By mid-2026, Software Advice’s monthly organic traffic value had fallen from $5.5M to $611K, GetApp’s from $3.3M to $233K. Those 2 alone bled about $8M a month in search value.
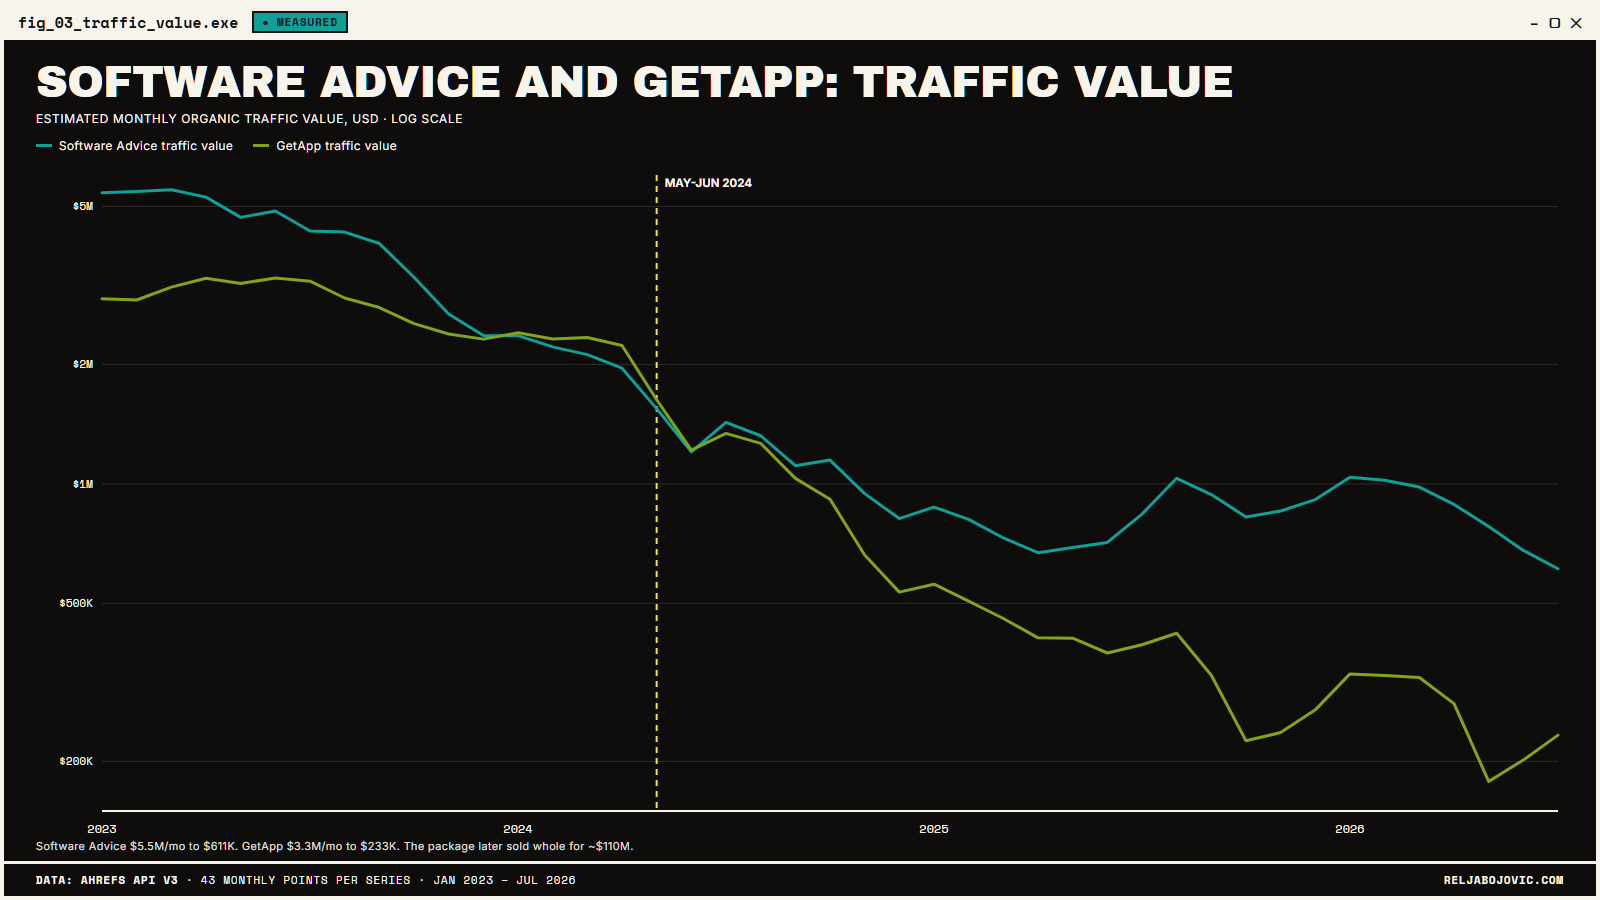
They were two-thirds of a package that sold, whole, for $110M - roughly 14 months of the search value just 2 of them used to generate. An asset trading at 14 months of its former output has been priced as a death certificate.
The suspects, cleared one by one
Every good murder mystery ends with a casual sitdown, with the detective rinsing everyone until the wrongdoer breaks. Let’s actually run the lineup, just like Agatha Christie herself intended.
Suspect 1: The content (“They were thin and they deserved it”)
It would be too simple, wouldn’t it? Instead of the same slop one would expect, we actually see both sides of the quality spectrum.
TrustRadius ran long-form structured reviews with verified reviewer identity - the site SEO people pointed at when they wanted to say “software X has stellar reviews.” GetApp ran auto-generated templates and prioritized conciseness over depth.
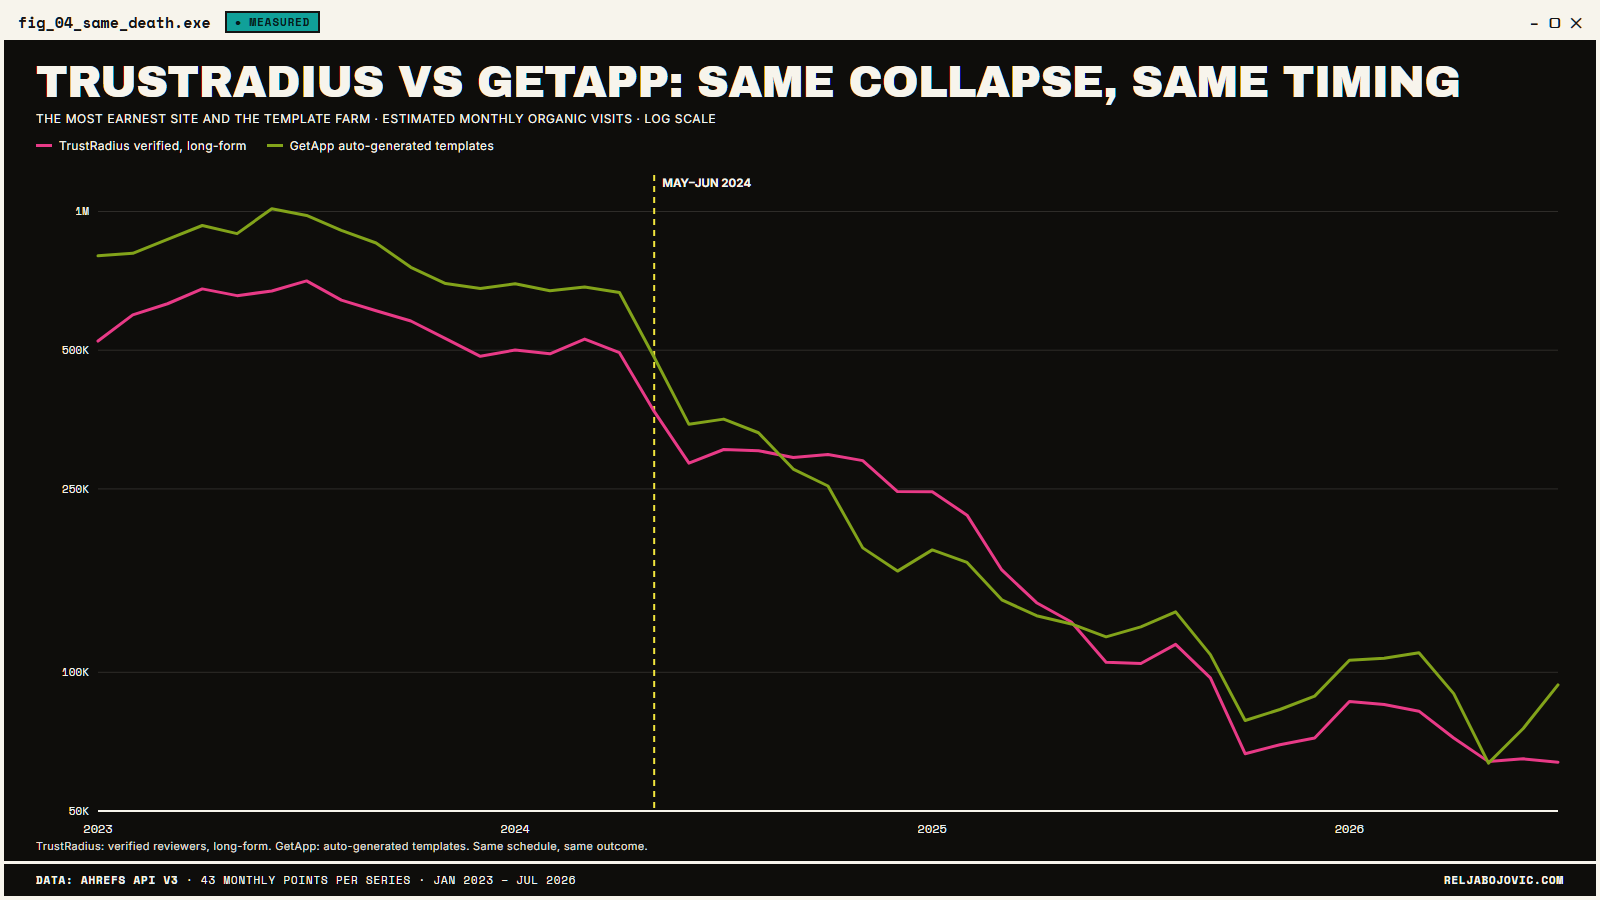
Same death, -91% each, same schedule. We can sit here all day and lament that quality content got nuked, but that doesn’t change the fact that someone pulled the trigger. Moving on:
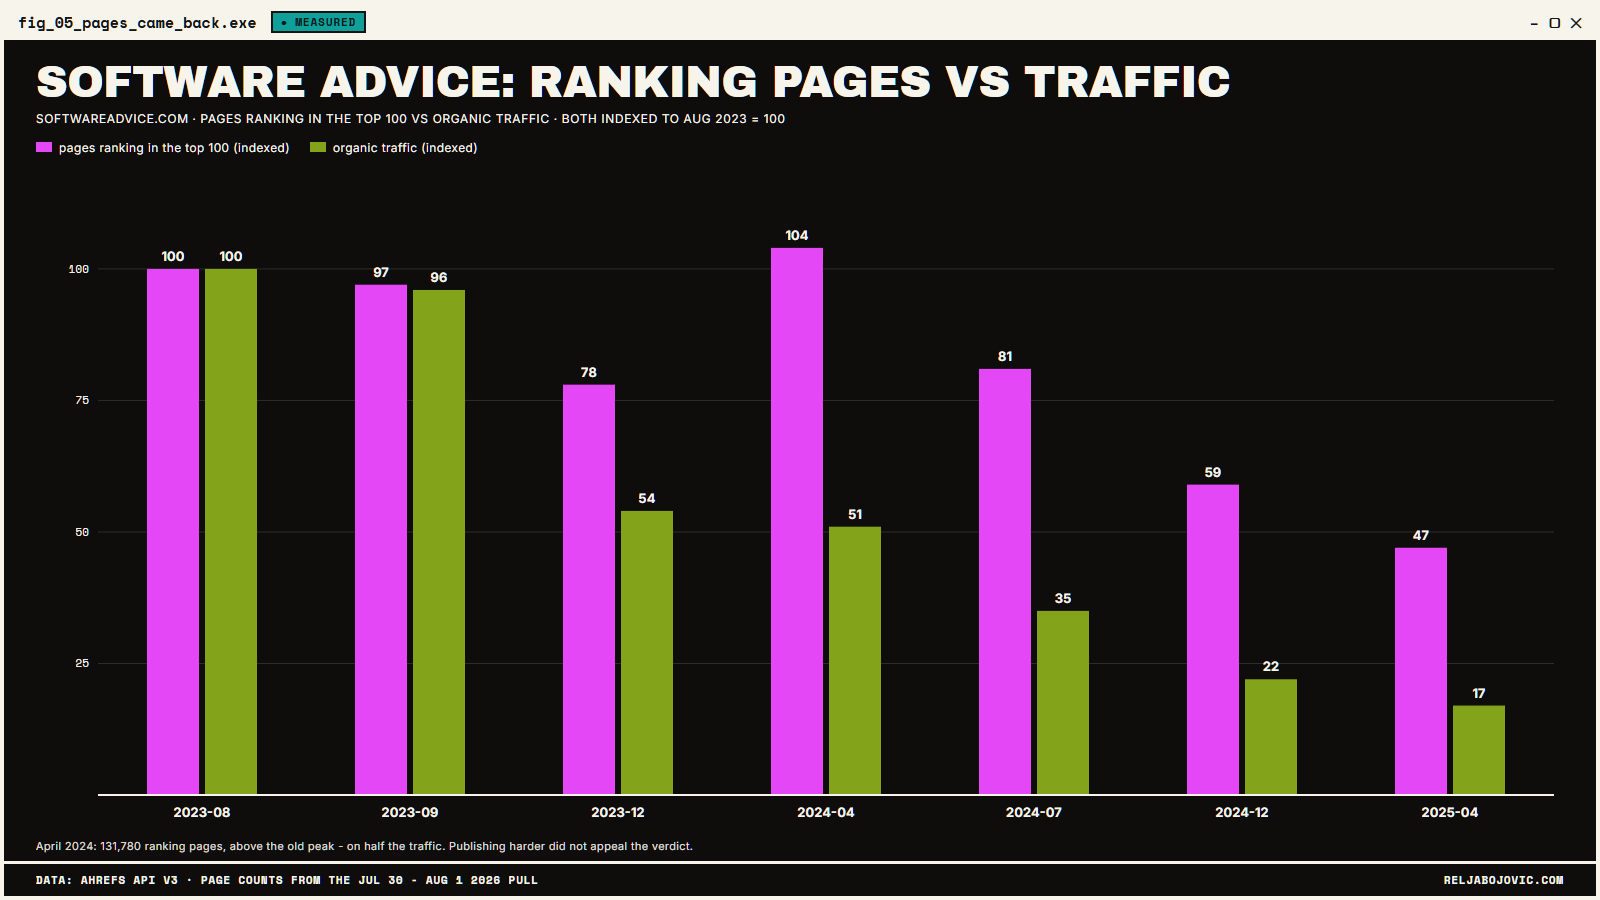
Software Advice makes it worse - by April 2024 it had rebuilt its ranking footprint to an all-time high - 131,780 pages in the top 100, above its old peak - while its traffic sat exactly where the first wound left it.
The verdict was already in, and publishing harder didn’t appeal it. This suspect is free to go.
Suspect 2: the links (“authority decays, they got outranked”)
I gotta be honest, I was expecting Biblical levels of greed here, but I couldn’t’ve been more wrong.
The domain ranking didn’t twitch: G2 went DR 90 to 91 while losing 74% of its traffic, and the same flat line runs across all 5 bodies.
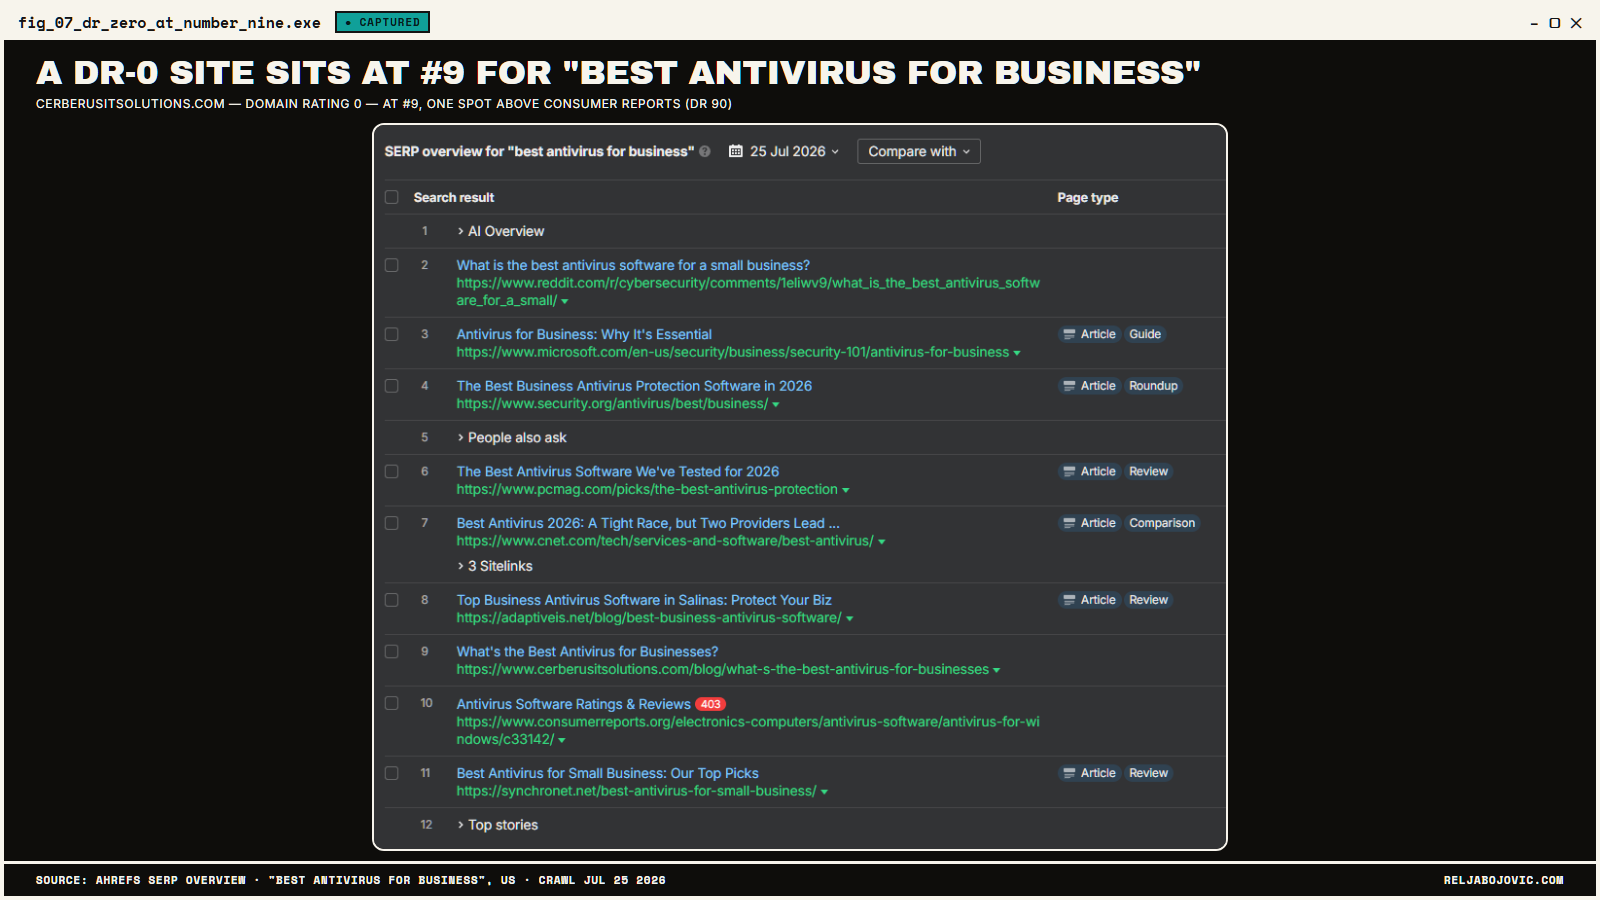
Okay, what about the SERPs they vacated? Now occupied by sites with a fraction of their authority - later in this piece, a DR 0 site ranks #9 for “best antivirus for business”, which should be impossible in every model your link vendor sells.
And the thing that completely exonerates links as the main suspect: GetApp’s 9 most-linked pages after the homepage hold 16,284 referring domains and earn 7 visits a month between them.
| Page | Ref. domains | Visits/mo | Top keyword (position) |
|---|---|---|---|
| /website-ecommerce-software/a/bandicut/ | 1,828 | 0 | bandicut (7) |
| /collaboration-software/a/videocom/ | 1,824 | 0 | videocom (4) |
| /sales-software/a/winmo/ | 1,821 | 1 | winmo pricing (11) |
| /industries-software/a/tinycat/ | 1,818 | 0 | tinycat library (8) |
| /customer-service-support-software/a/livechat/ | 1,810 | 1 | live chat. com (7) |
| /marketing-software/a/taplink/ | 1,806 | 4 | what is taplink (10) |
| /website-ecommerce-software/a/imovie/ | 1,797 | 1 | imovie cost (5) |
| /construction-software/a/buildtools-construction-mgmt/ | 1,795 | 0 | buildtools (24) |
| /hr-employee-management-software/a/simpo/ | 1,785 | 0 | simpo (1) |
1 observation I’ll just leave here: the most-linked pages across all 5 sites are the same dozen obscure products, each in an implausibly tight band of ~1,800 referring domains. Make of that what you will. *wink wink*
Suspect 3: The buyers and AI are colluding (“nobody reads reviews anymore”)
While Claude may or may not have had a large impact on which SaaS subscriptions I add and drop, that’s not the case with everyone.
In fact, people ask Google which software to buy more today than at any point in history: 12 of the 13 head terms I pulled volume history for are flat-to-up since 2023 - “crm software” +267%, “payroll software” +208%, “project management software” +88%.
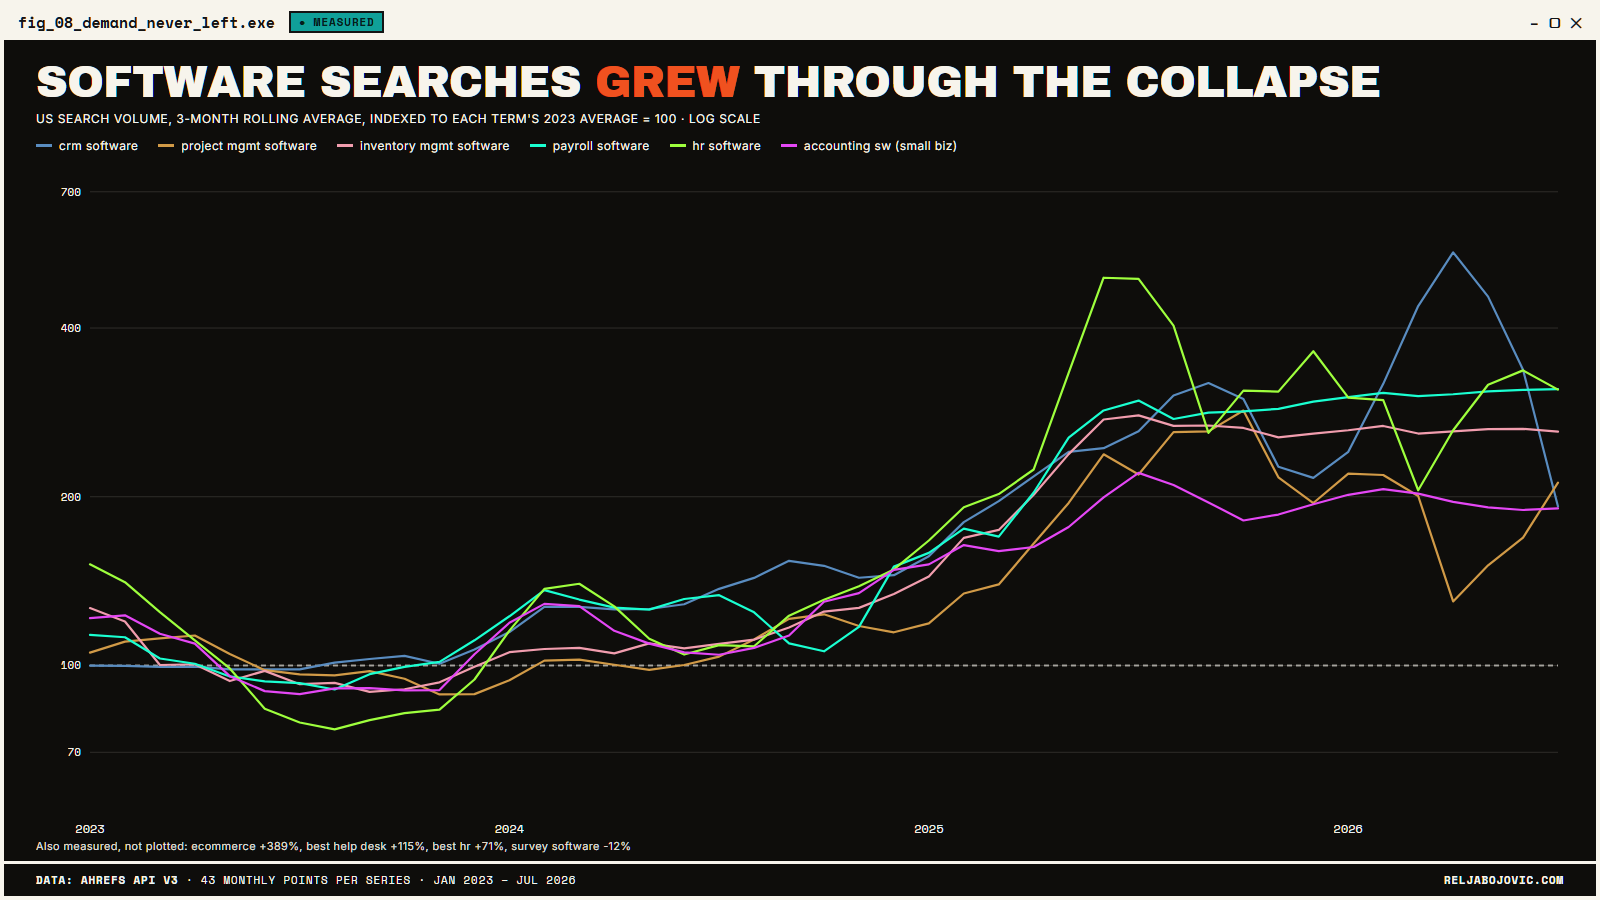
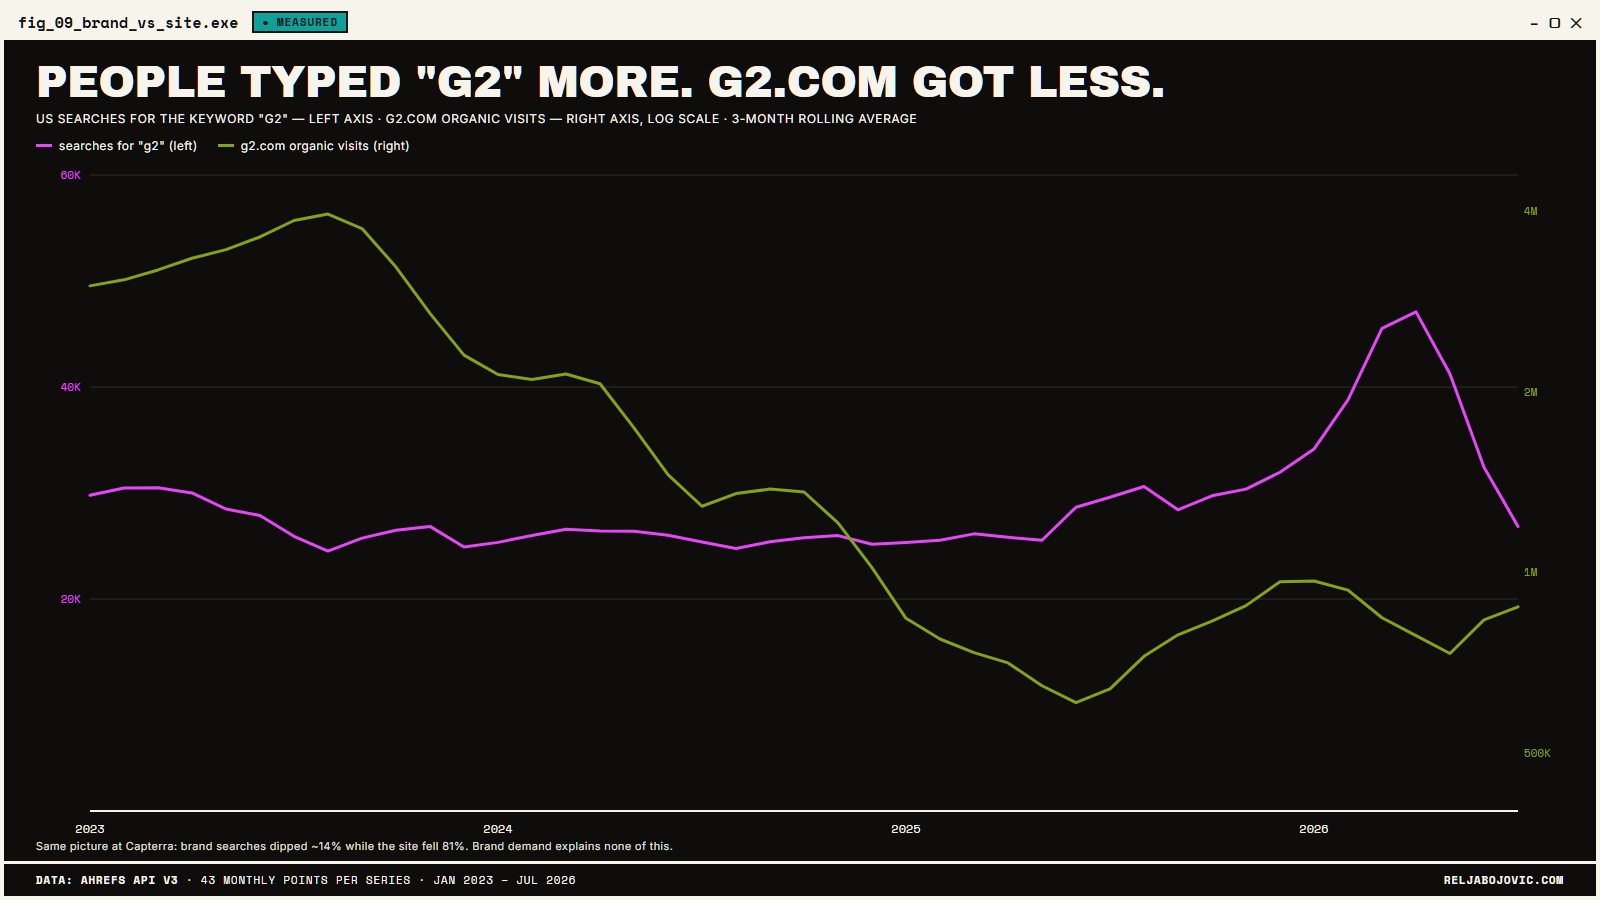
Even the referees’ own names held: “capterra” searches dipped 14% while the site fell 81%, and “g2” GREW 39% (yearning for human input again, are we?) against a 74% collapse. The demand side of this market never blinked while the supply of clicks got quietly discontinued.
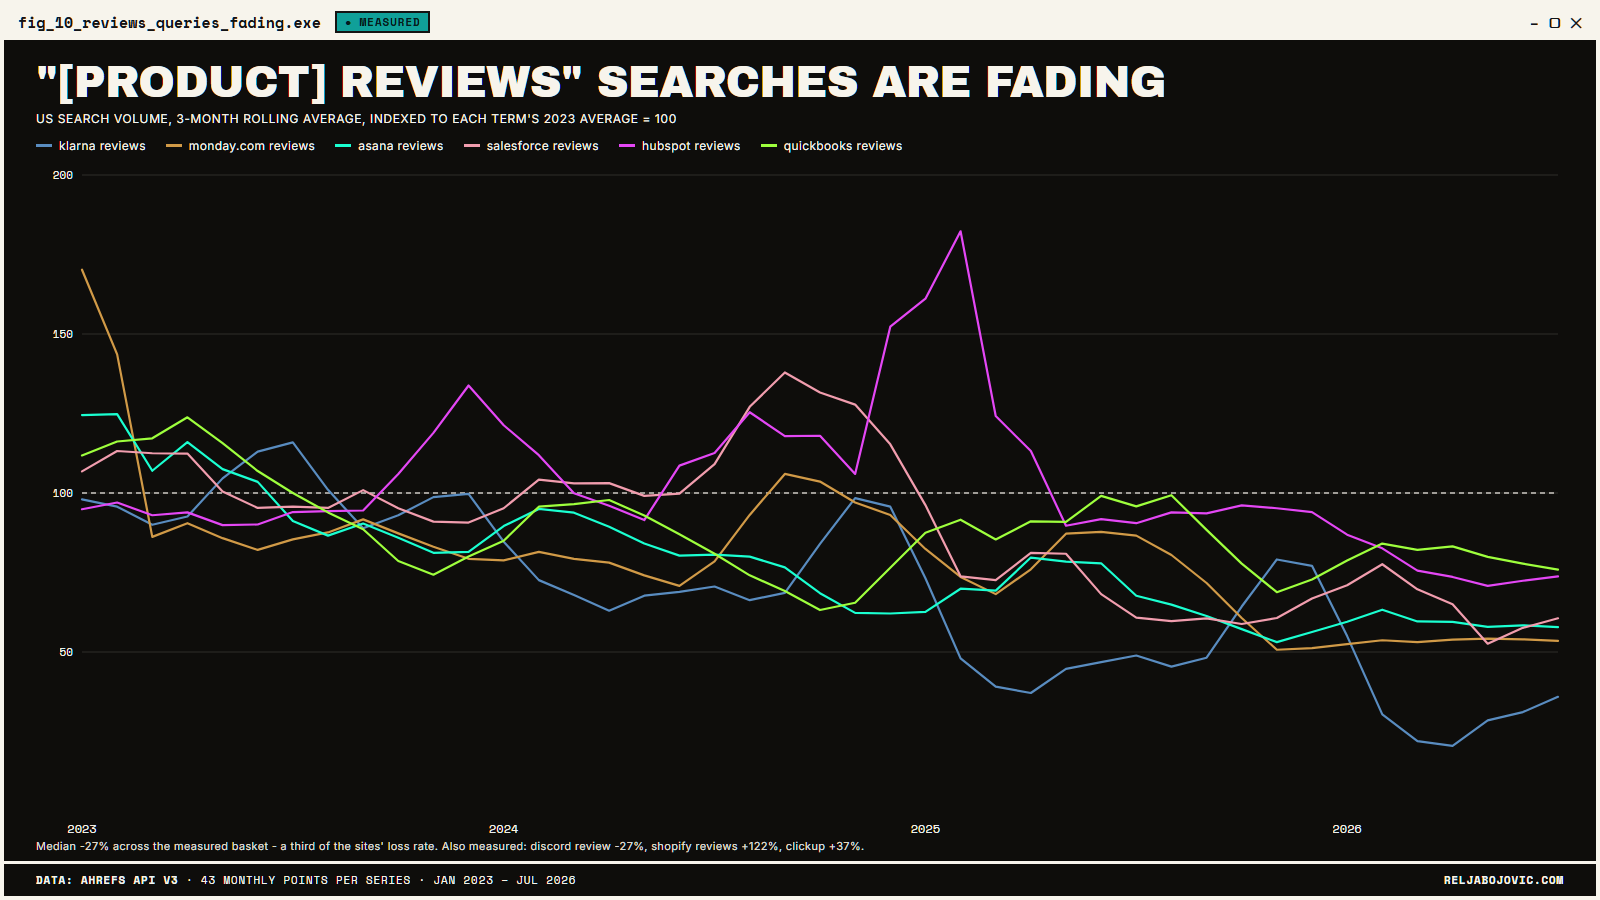
1 nuance, because I checked: “<product> reviews” queries really are fading - down a median 27%, a third of the sites’ loss rate. GetApp still managed to lose “appfolio reviews” from #1 while 1,000 people a month were typing it.
To reiterate: despite LLM-induced brainrot, search volumes are up across the board, which means this suspect won’t be spending the night in a cell. Next!
Suspect 4: the obvious one (“AI Overviews ate the clicks”)
Might as well send him to court right away, eh? Not so fast. Here’s the alibi: capterra.fr lost 81% of its traffic in a country where AI Overviews didn’t exist until 5 weeks ago. France sat out the entire AIO era over a copyright fight, and the French corpse looks exactly like the American one, on the same calendar.
And France isn’t the exception. I lined up every localized body that died against the date AI Overviews reached its country, and I found that 6 of the 9 died before the weapon was in the room:
| Body | Started dying | AIO arrived there | Lag |
|---|---|---|---|
| capterra.fr | Oct 2024 | Jul 2026 | -21 months |
| getapp.fr | Aug 2024 | Jul 2026 | -23 months |
| getapp.es | Jun 2024 | Mar 2025 | -9 months |
| capterra.it | Aug 2024 | Mar 2025 | -7 months |
| getapp.de | Aug 2024 | Mar 2025 | -7 months |
| capterra.ca | Jun 2024 | Oct 2024 | -4 months |
| capterra.com.br | Aug 2024 | Aug 2024 | 0 months |
| capterra.in | Sep 2024 | Aug 2024 | +1 month |
| getapp.co.uk | Dec 2024 | Aug 2024 | +4 months |
“Started dying” = the first month traffic closed more than 25% below the site’s January-March 2024 average
The May-June 2024 wound lands simultaneously in the US, Canada, Brazil, Spain and France - markets that were 4, 2, 9 and 25 months away from the feature. If you’re wondering - no, treatment didn’t predict death either: the UK got boxes in August 2024 and capterra.co.uk never died, while capterra.jp grew 39% - quite the murder weapon.
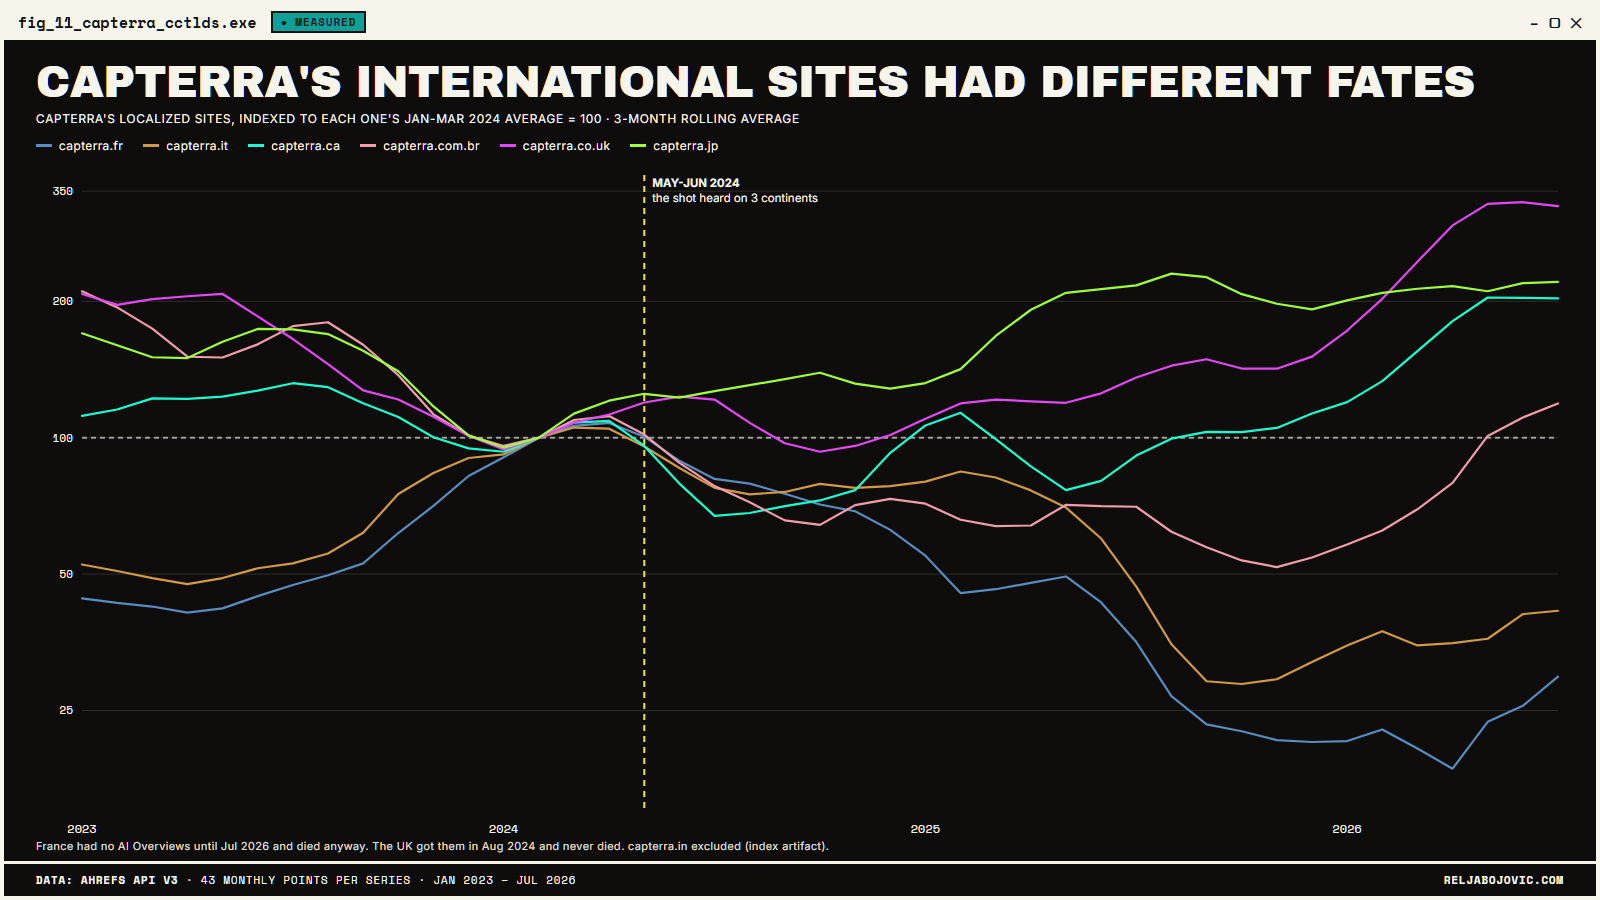
Here’s where it gets weird - a US-only feature can’t move French and Canadian traffic in the same fortnight. Whatever fired the first shot shipped worldwide on one day - and the things that ship like that are Google’s core updates and spam policies, not its AI features, which spent 2 years crawling country by country.
Cleared as the lone gunman, but their DNA was found at the crime scene. Told not to leave town.
Every suspect walks. 5 bodies, 1 grave, 80% of an industry’s audience gone - time for forensics instead of vibes.
5 playbooks, 1 grave
When ClickUp’s blog traffic collapsed 97.6%, it was mainly due to content-related shenanigans. As I said in the intro, that’s the one story you can’t tell about these 5: the most earnest site in the category died the same death as the laziest.
However, every good detective researches the victim to find clues and instances where the killer may have slipped. So, let’s meet them, shall we?
Capterra: the expander
Capterra rode straight into the March 2024 core update, doubling from 126K ranking pages in January to 269K by April - the ClickUp move, a year early, at directory scale, executed with total confidence, which is the bravest possible way to be wrong.
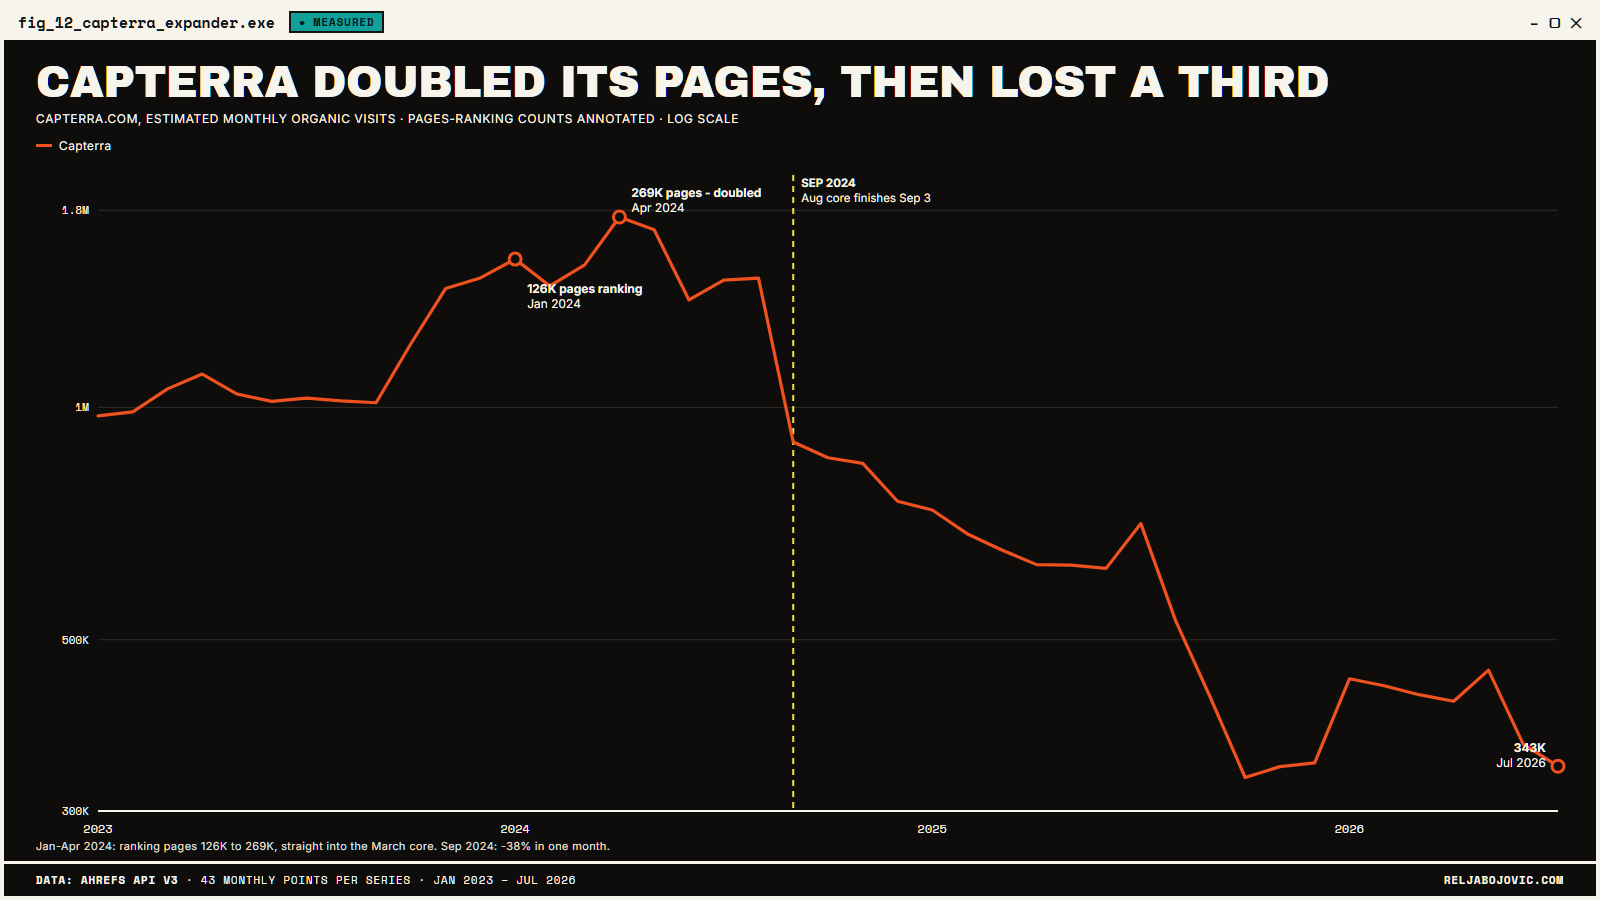
It looked immune for 5 months. Then the August core finished rolling out and a third of its traffic left in 30 days - 27 of its 35 biggest losing pages were the /{category}-software/ directories, the product itself. Expansion bought 5 months of grace and a steeper cliff, which is what expansion usually buys.
Software Advice: the rebuilder
Shot earliest, late 2023, before the famous updates - and what died first is the tell nobody read at the time: vendor-profile pages ranking for other companies’ brand queries. “tally prime” #9 to #47, “adp run” #2 to #16. Google was repossessing borrowed doorways 5 months before the first headline.
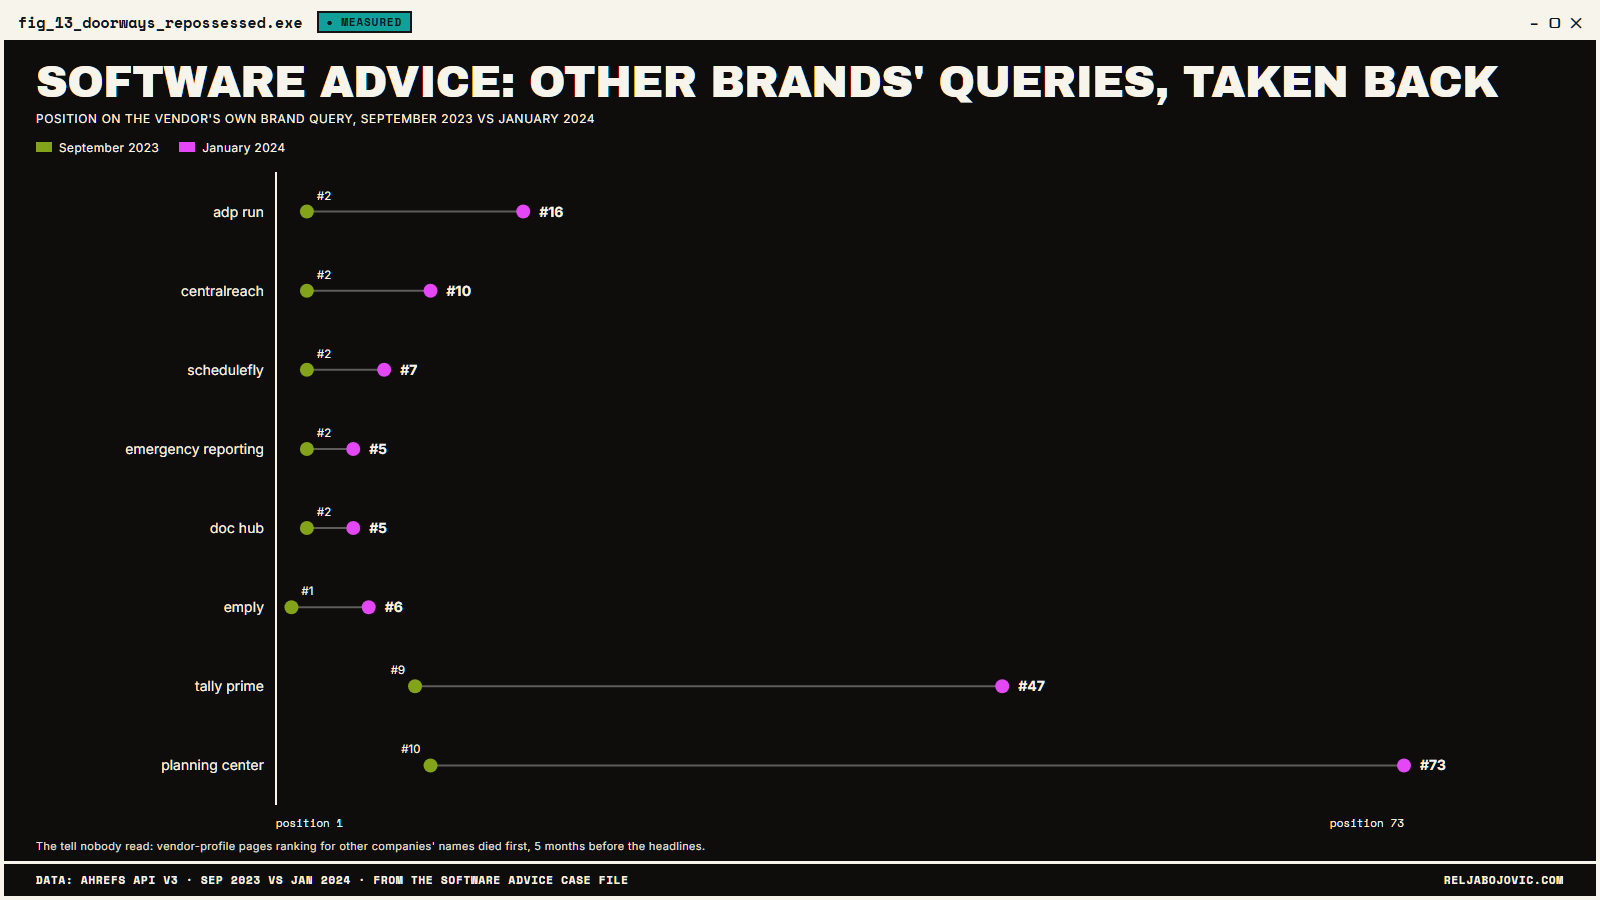
Its response - rebuild the footprint to an all-time high - is the single most instructive failure in the study: volume doesn’t appeal a verdict. That lesson has been sitting in public data for 2 years and the content industry still refuses delivery.
G2: the pivoter
G2 was the only one that visibly fought back: learn.g2.com pivoted to first-person, I-tested-this content with human bylines - precisely the format the Helpful Content era claimed to reward.
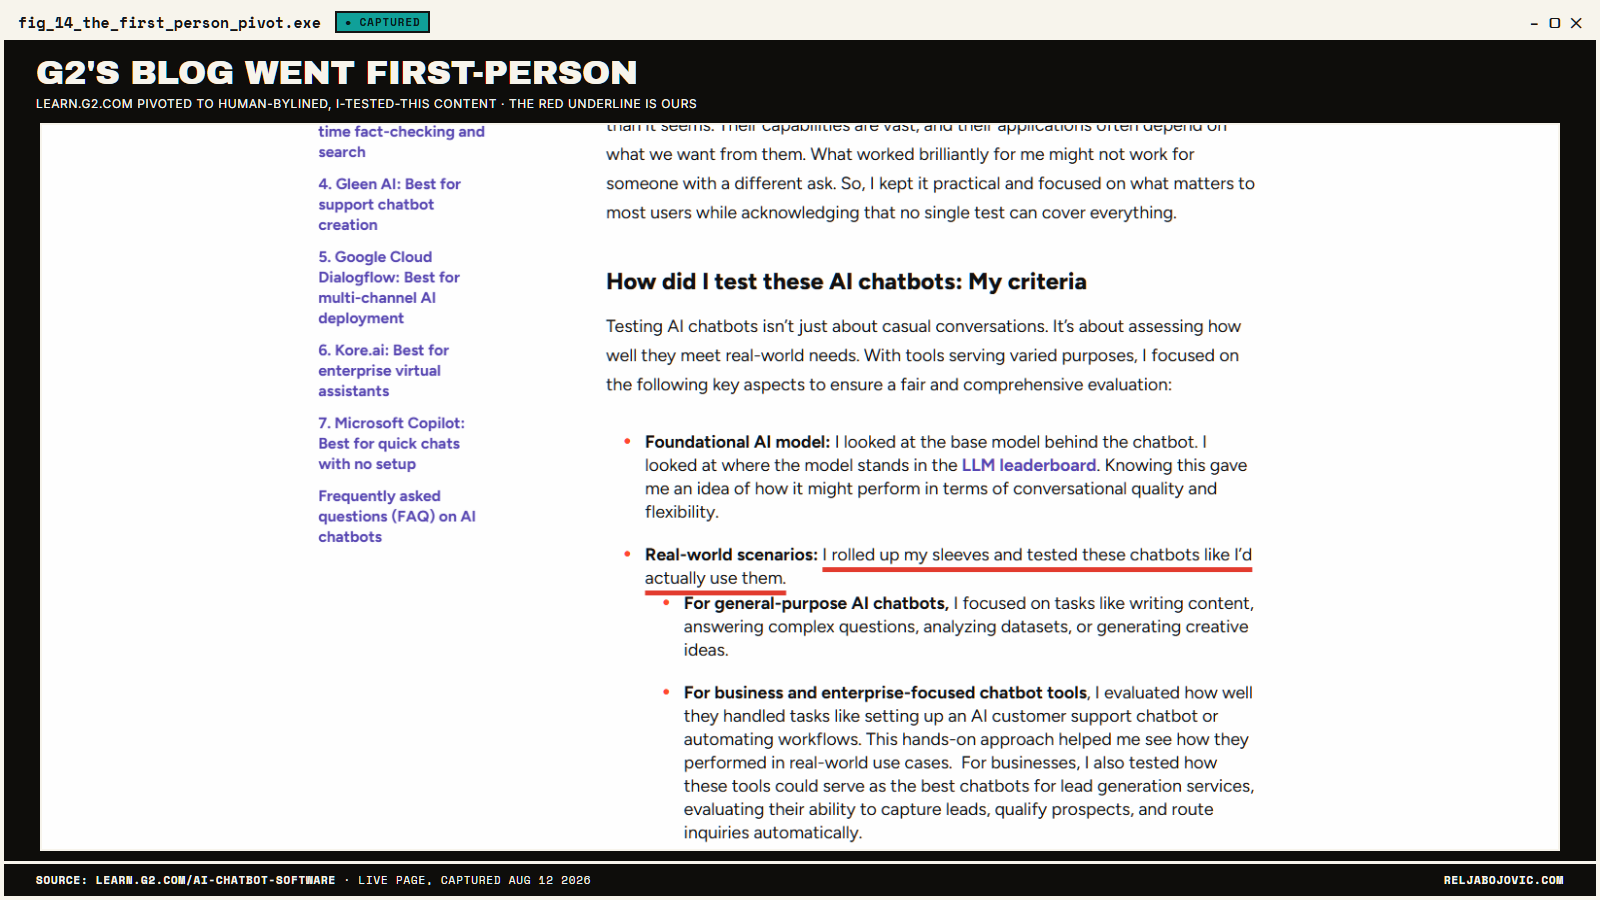
It was the right move, executed 3 years late, and Google had stopped grading homework. (Gaetano DiNardi’s G2 teardown pins the whole story on the 2023 wound - he’s right about the date, and the date turns out to be leg 1 of 3.)
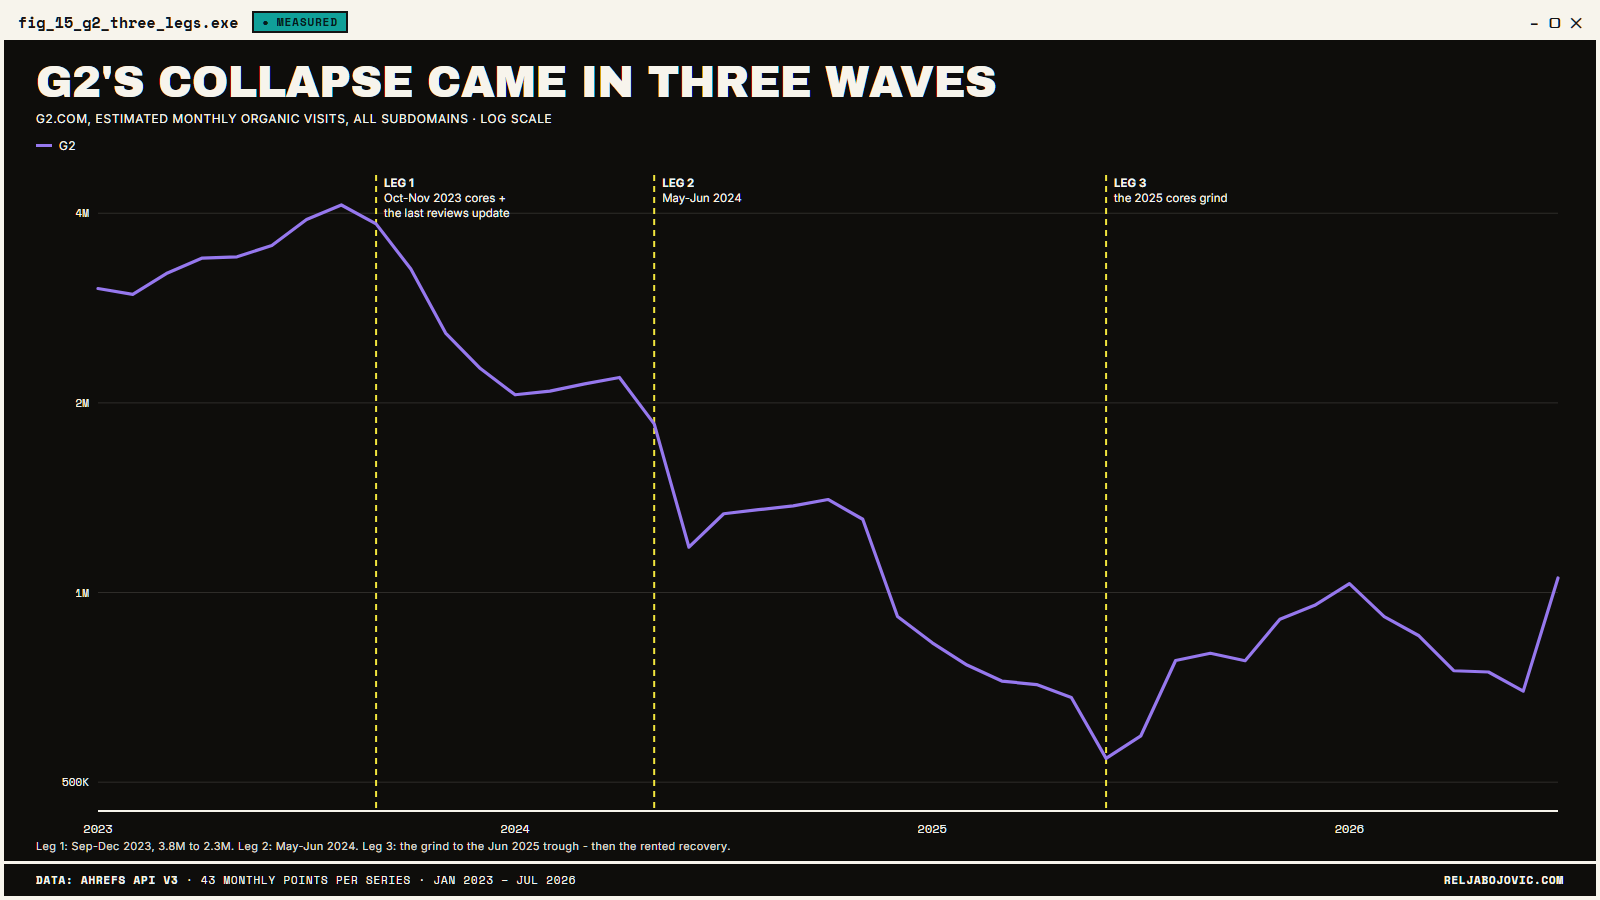
Its curve turned anyway: 545K at the June 2025 trough to just over 1M by January 2026. On any slide in any board deck, that’s a recovery. But hold that thought for a minute - the “recovery” gets its own scene, and it’s the best scene in the movie.
GetApp: the template
This is perhaps the fastest death in the entire set: May-June 2024, traffic -47% while the page footprint moved -3%. Same site, same pages, same index - head cut off.
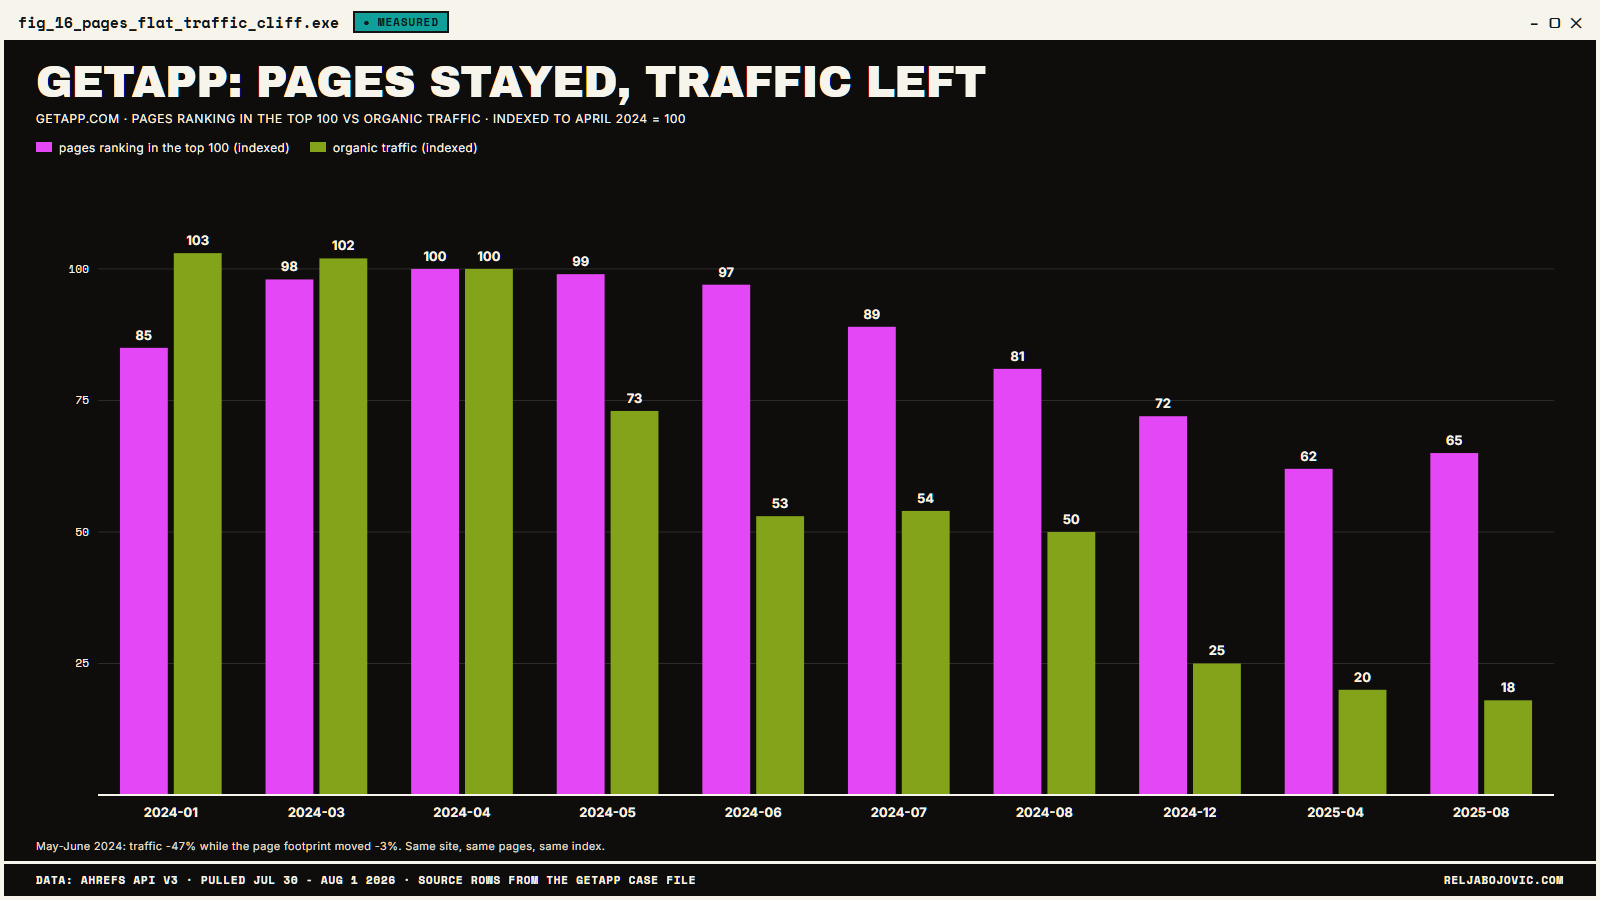
12 of its 13 biggest-losing auto-generated sub-pages now rank for zero keywords, including “appfolio reviews” and “discord review”, both formerly #1:
| Page | Top keyword (Aug 2024) | Was | Now |
|---|---|---|---|
| /a/klarna/reviews/ | klarna reviews | #1 | gone |
| /a/appfolio-property-manager/reviews/ | appfolio reviews | #1 | gone |
| /a/discord/reviews/ | discord review | #1 | gone |
| /a/stripe/reviews/ | stripe reviews | #3 | gone |
| /a/ziprecruiter/reviews/ | ziprecruiter | #3 | gone |
| /a/tripactions/pricing/ | navan pricing | #7 | #7 - and 448 → 13 visits |
A review site that can’t rank for “<product> reviews” is a bakery that’s been legally barred from bread. You could’ve started tombstone shopping in mid-2024 already.
TrustRadius: the bystander
TrustRadius is the one that hurts to look at. No expansion, no pivot, no rebuild - verified reviewers and long-form reviews, which earn them the #1 spot for “real estate software”, “contact center platform”, “data warehouse software”. Sadly, this approach was in vain.
It died in 2 moves: May-June 2024 took -40% in 60 days with every page still indexed - same inventory, worse shelf. October 2025 deleted the leftovers: 140,801 pages fell out of the top 100 and took only ~30,000 visits with them, because the money had already been gone for a year.
Now, a site famed for its reviews is only 8.9% review traffic:
| Page type | Pages in top 25 | Visits/mo | Share |
|---|---|---|---|
| Pricing pages (other vendors’ prices) | 14 | 9,375 | 52.2% |
| Its own homepage (brand) | 1 | 3,449 | 19.2% |
| Blog articles | 4 | 2,889 | 16.1% |
| Review pages | 4 | 1,604 | 8.9% |
| Category pages | 1 | 383 | 2.1% |
| A PDF on media.trustradius.com | 1 | 275 | 1.5% |
Today all 6 category hubs are absent from the top 100 - not demoted, gone - and its 27 biggest non-brand keywords fell from 23,354 monthly visits to 30. The site that did everything right ties the template farm at -91%. RIP.
The rundown
| Site | Sold | Strategy under fire | Outcome |
|---|---|---|---|
| Capterra | category directories | expanded 126K to 269K pages into the update | -81% |
| Software Advice | vendor profiles + editorial | rebuilt footprint to all-time high | -85% |
| G2 | reviews + categories | pivoted to first-person editorial | -74% |
| GetApp | auto-templates | nothing visible | -91% |
| TrustRadius | structured reviews | nothing visible | -91% |
5 rows, 5 behaviors, 1 column that doesn’t vary. No matter what anyone did, they couldn’t fight off the killer. Now, it’s time to see who the maniac really is…
Who killed B2B software reviews and how
Sometimes, our gut feelings turn out to be true. Any wide-ranging effects that destroy multiple sites in the same niche, regardless of size, strategy, approach and ownership, can only come from one place - Google. Thought you were getting away with this one, eh? Cuff ‘em, boys!
But wait, how did Google pull it off?
Stage 1: the global demotion
The 2023 wounds hit the 2 sites most exposed to the reviews-update era. Then May-June 2024 fired the same shot at everyone, everywhere, at once:
| Site (May-Jul 2024) | top 3 | top 4-10 | top 21-50 |
|---|---|---|---|
| G2 | -39.9% | -26.0% | -5.4% |
| GetApp | -44.6% | -36.8% | -6.5% (top 11+) |
| Software Advice | -45.6% | -33.7% | -12.8% |
| Capterra (Sep 2024, the late bill) | -38.8% | -31.0% | -15.0% (top 11+) |
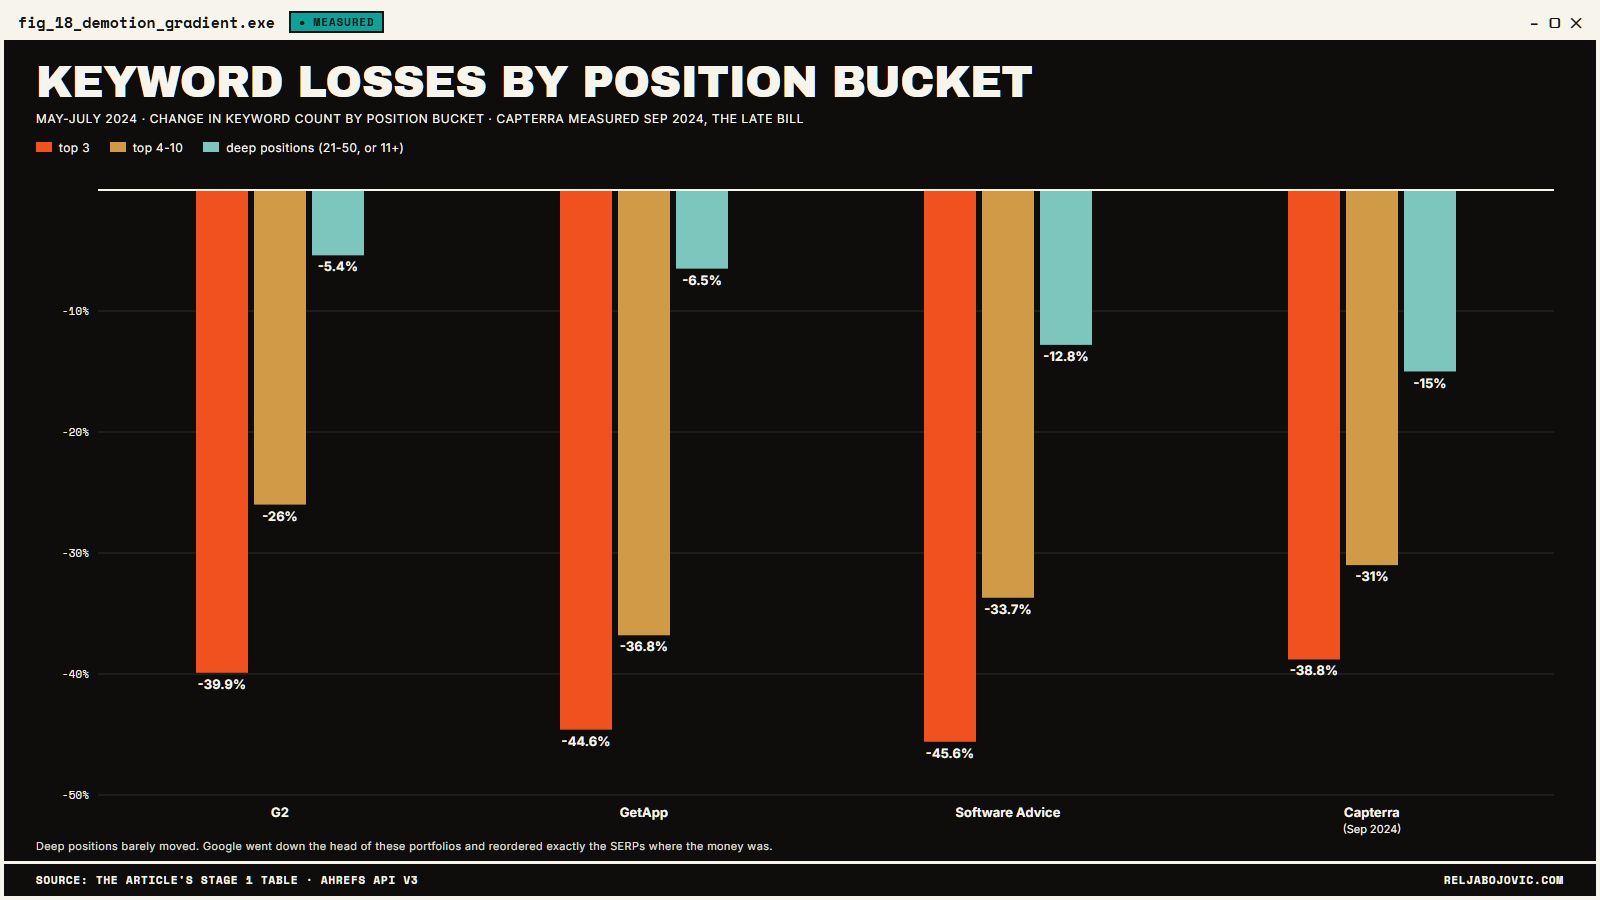
The better a keyword ranked, the harder it fell, while the deep positions barely moved - Google went down the head of these portfolios and reordered exactly the SERPs where the money was. A head-shot administered 5 times with the same grouping, on 3 continents, in 60 days.
Stage 2: the answer box moves in
Where the new SERP features deployed, the demoted seats stopped paying at all. For instance:
- GetApp has held #7 for “navan pricing” for 2 years straight - a real blue link, not a phantom - and its clicks went from 448 a month to 13.
- Software Advice’s /veterinary/ page was organic #1 for “veterinary software reviews” in August 2024, earning 67 visits. It still sits on page 1 today, at #7 - for 10 visits a month.
- The month AI Overviews reached Capterra’s SERPs, 8 of its 25 biggest-losing pages lost 73-95% of their clicks with zero rank change.
- PCMag holds a genuine organic #2 for “antivirus software”, directly under an answer box that doesn’t quote it - traffic on that keyword: 8,092 to 0.
- Investopedia sits at a genuine organic #3 for “ebitda” under a box - 23,606 monthly visits down to 1,357.
We also have other proof AI Overviews are to blame: Ahrefs’ own controlled study puts the position-1 click penalty under a box at -58% - “navan pricing” just shows you what that abstraction does to a real page’s rent.
The timeline
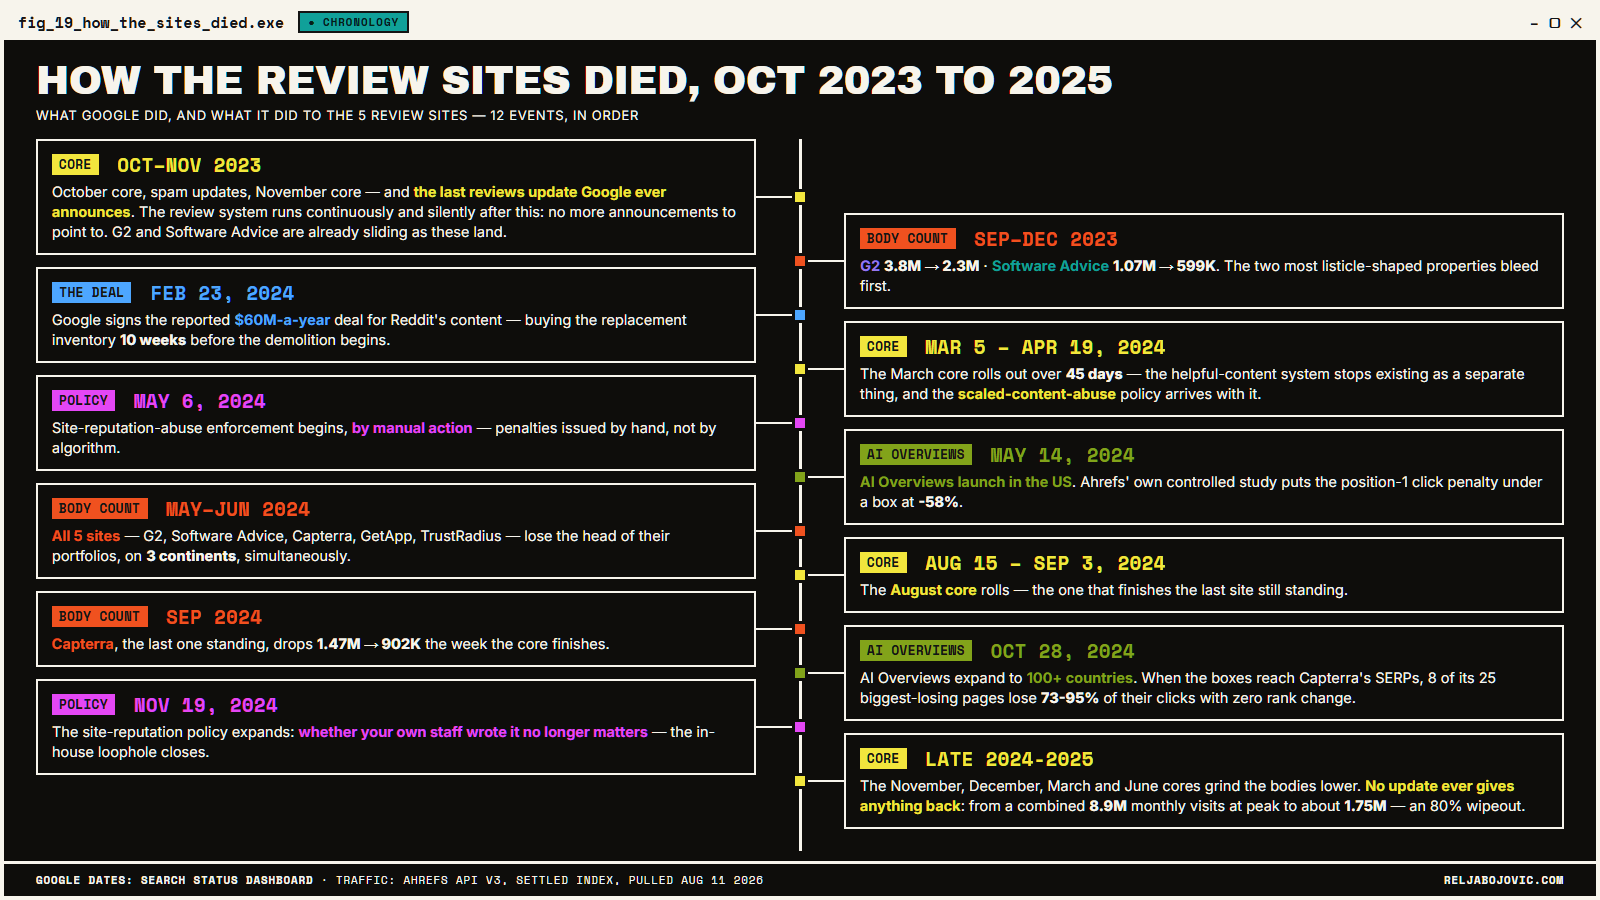
For those of y’all that like things chronologically:
- October-November 2023 - the October core + spam updates, the November core, and the November reviews update - the last reviews update Google ever announces; the system runs continuously after this.
- September-December 2023 - G2 loses 3.8M → 2.3M. Software Advice loses 1.07M → 599K. The 2 most listicle-shaped properties bleed first.
- February 23, 2024 - Google signs a reported $60M-a-year deal for Reddit’s content.
- March 5 - April 19, 2024 - the March core rolls out over 45 days, absorbing the helpful-content system and introducing the scaled-content-abuse policy.
- May 6, 2024 - site-reputation-abuse enforcement begins, by manual action.
- May 14, 2024 - AI Overviews launch in the US.
- May-June 2024 - all 5 review sites lose the head of their portfolios, on 3 continents, simultaneously.
- August 15 - September 3, 2024 - the August core.
- September 2024 - Capterra, the last one standing, drops 1.47M → 902K the week the core finishes.
- October 28, 2024 - AI Overviews expand to 100+ countries.
- November 19, 2024 - the site-reputation policy expands: whether your own staff wrote the content no longer matters.
- Late 2024 - 2025 - the November, December, March and June cores grind the bodies lower. No update ever gives anything back.
The pricing conundrum
The box has another tell: on pricing SERPs it fires almost exactly where the vendor hides the price - Workday, NetSuite, ADP, Navan, Birdeye. Publish a clean price and you keep #1 with no box at all.
I checked 24 pricing SERPs by hand. The box sits on 11, and across the roughly 100 sources those boxes cite, the 5 review sites appear 0 times.
Who does get quoted: the vendor’s own pricing page, Reddit, procurement startups (Vendr, Spendbase, Spendflo, CloudEagle), competitors blogging about each other’s prices - PandaDoc explaining DocuSign’s - and YouTube.
The blue links agree: across all 24 SERPs, the 5 sites crack the top 10 on just 4, and the only real review-directory listings left are on “navan pricing” and “birdeye pricing” - the 2 vendors that won’t say the number. The industry’s final shelf is the tax collector’s office.
Proof beyond the fruitless five
If Google were just making everyone poorer, every collapse would look the same. They don’t - deaths have fingerprints, and the 5 share one.
saasworthy.com is the sixth confirmation: both legs, the 5’s exact dates, the 5’s exact gradient, -86% - and its “hotschedules pricing” page improved #4 to #1 on the rank tracker - the #1 is an answer-box artifact, the live organic rank is #5 - while losing 98.3% of its clicks.
The morgue’s other drawers hold different signatures:
| Site | Drop | Signature |
|---|---|---|
| saasworthy.com | -86% | the execution: head-first gradient |
| softwaretestinghelp.com | -98.9% | the farm kill: every bucket at once, Sep 2023 |
| slant.co | -99.4% | the farm kill, same era |
| financesonline.com | -100.0% | the switch-off: 303,699 visits to 6, ranks #49 for its own name |
| alternativeto.net | -90% | the misread: real 2024 wound + a popped NSFW-AI bubble |
alternativeto deserves the footnote, because the genre keeps citing it wrong: its famous Jan 2025 cliff is mostly Google purging an NSFW-AI traffic layer - the biggest loser Ahrefs will even name is “ai undresser” (#3 → #21) - stacked on a real May 2024 head-shot. G2’s rented recovery, as a whole site.
4 different deaths, and your rank tracker flattens them all into the same red line and calls it a day.
And the knife on the table: there’s a third signature in late 2025 - the long tail vanishing everywhere at once - that I’m deliberately not building on, because it fires identically in France where Google changed nothing. That’s the coroner’s instrument and some of the most-shared collapse charts of last year are built directly on it.
The false happy ending: the rented recovery
“But wait, Relja, G2 made a comeback! Didn’t you see?”
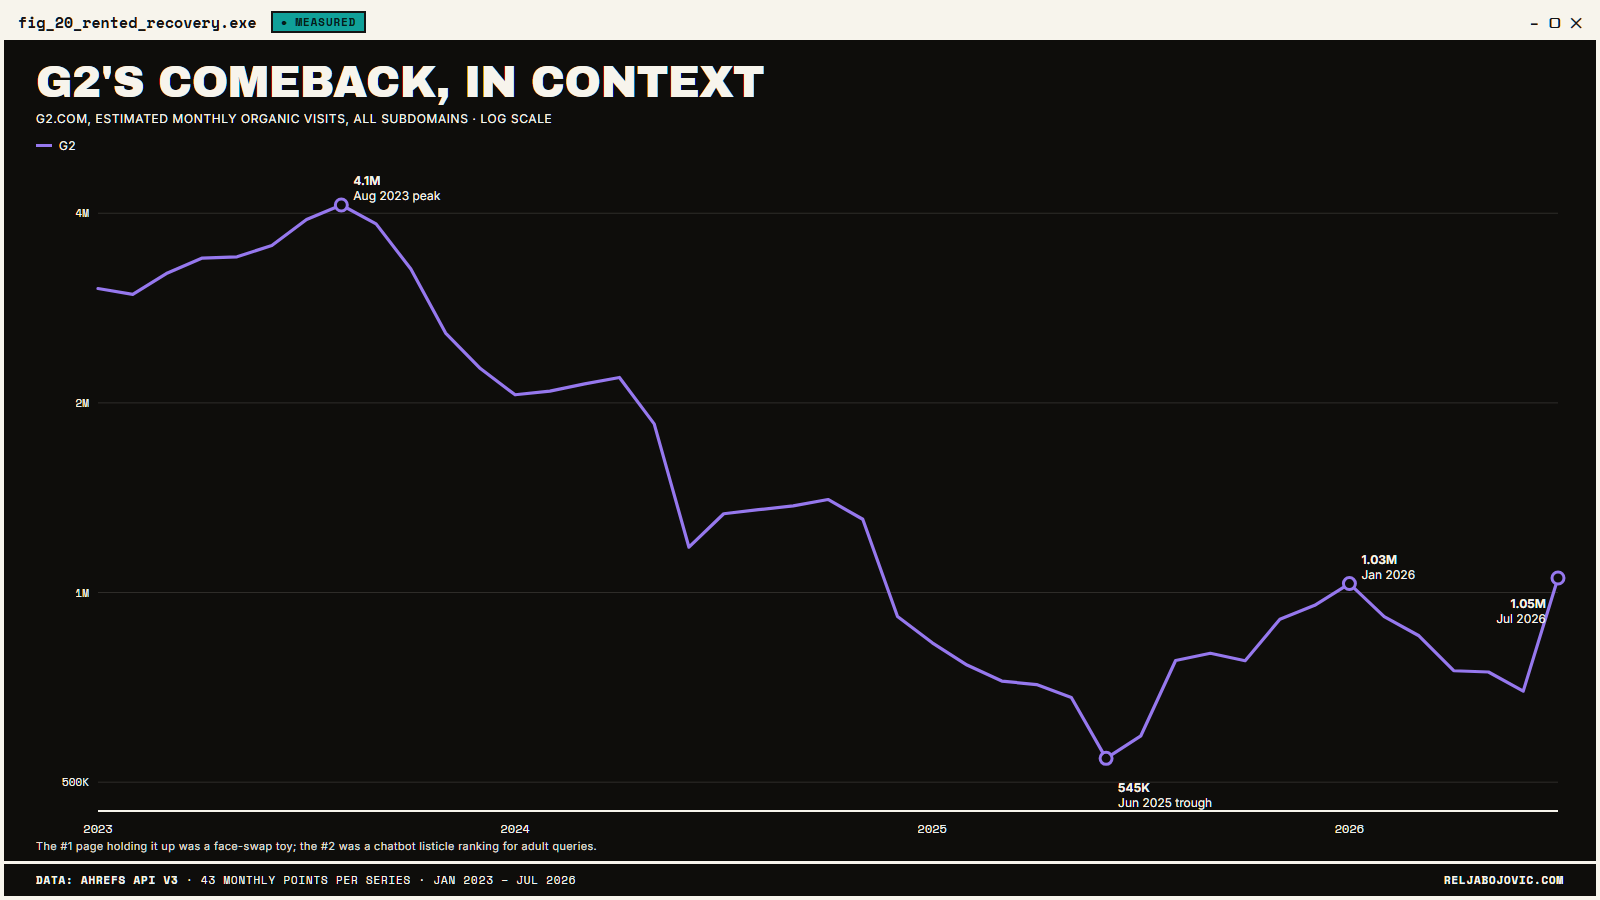
Yes, yes, I know. They bounced back, from 545K to a million in 7 months. The pivot got rewarded, quality content works, case closed. This curve got cited everywhere as proof of redemption, and I understand why: it’s the only hopeful line in 43 months of morgue photography. But let’s hold the applause for a bit, eh?
What was holding it up
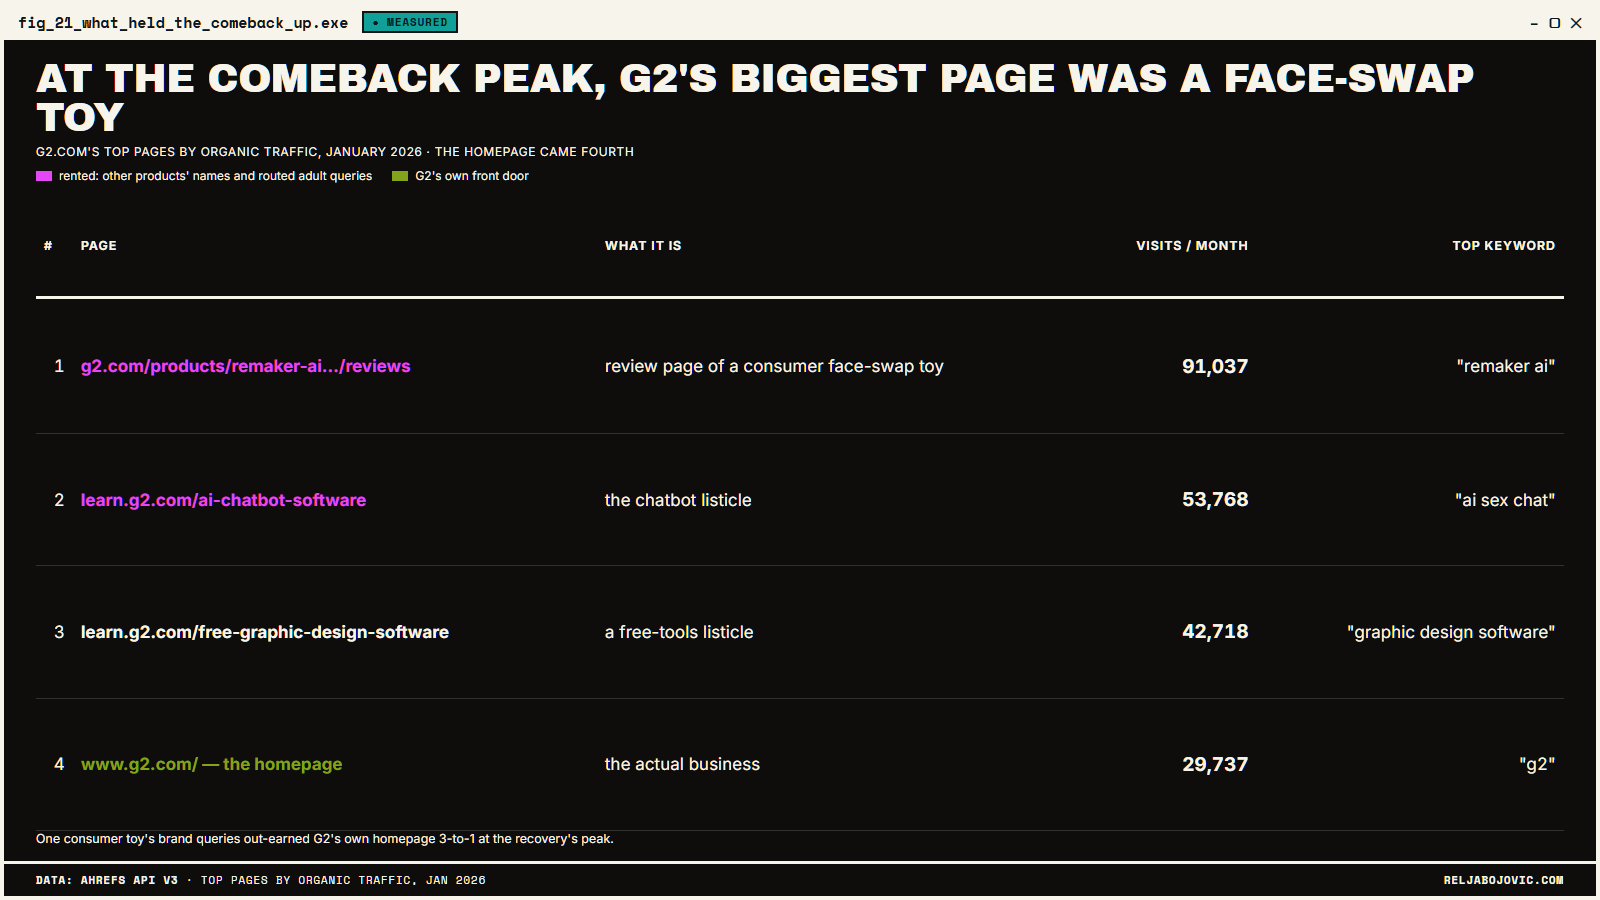
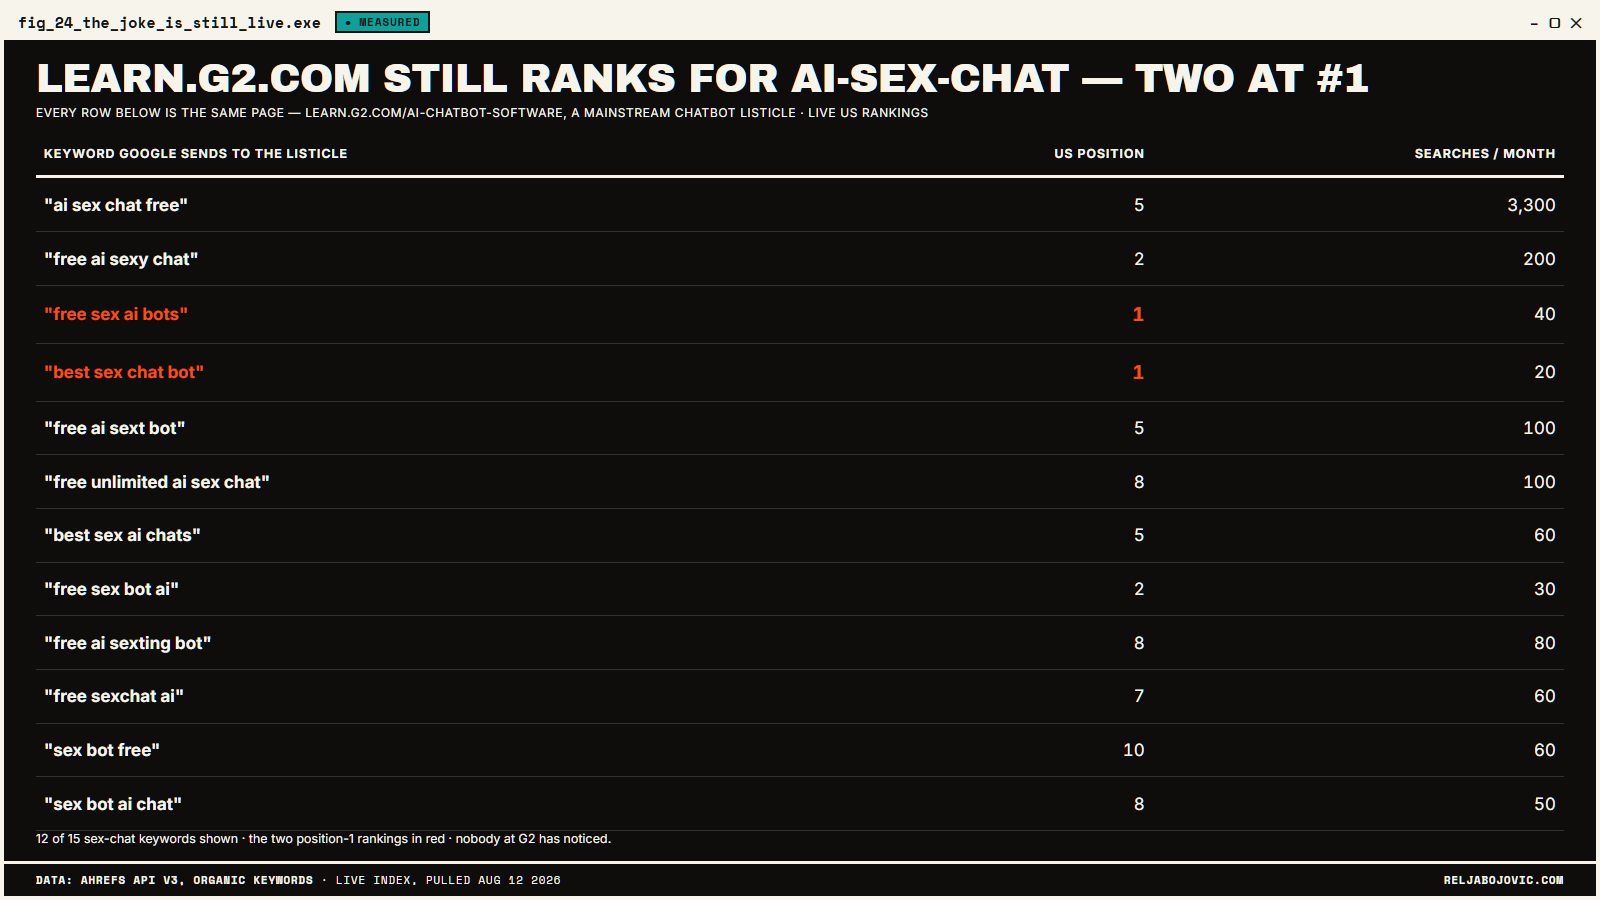
The #1 traffic page on g2.com during the recovery was the review page of Remaker AI, a consumer face-swap toy - 91,037 visits a month, more than G2’s own homepage. The #2 page on the entire domain was a chatbot listicle earning 53,768 a month whose top keyword was “ai sex chat”.
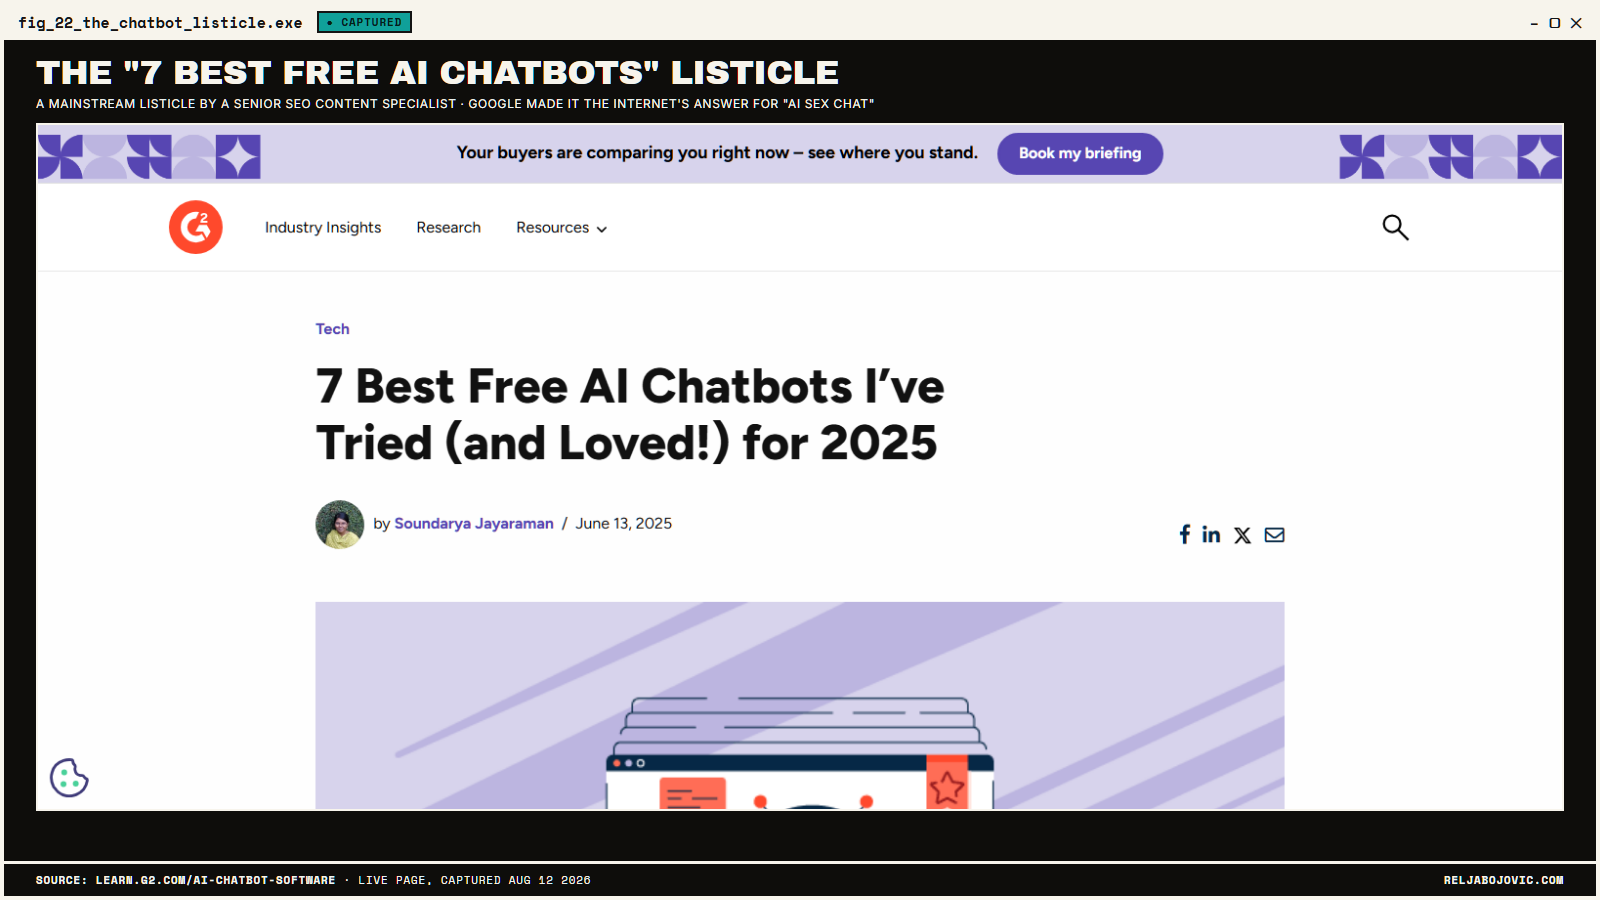
To be fair to whoever holds the pen at learn.g2: they never wrote a sex-chat page. They wrote “7 Best Free AI Chatbots I’ve Tried (and Loved!)”, a perfectly mainstream listicle by a Senior SEO Content Specialist, and Google’s matching engine decided it was the internet’s best answer for horny chatbot queries.
The B2B marketplace with Salesforce on the cap table spent its redemption arc propped up by face-swap tools and misrouted adult intent. Nobody put THAT on the board slide.
Rent comes due
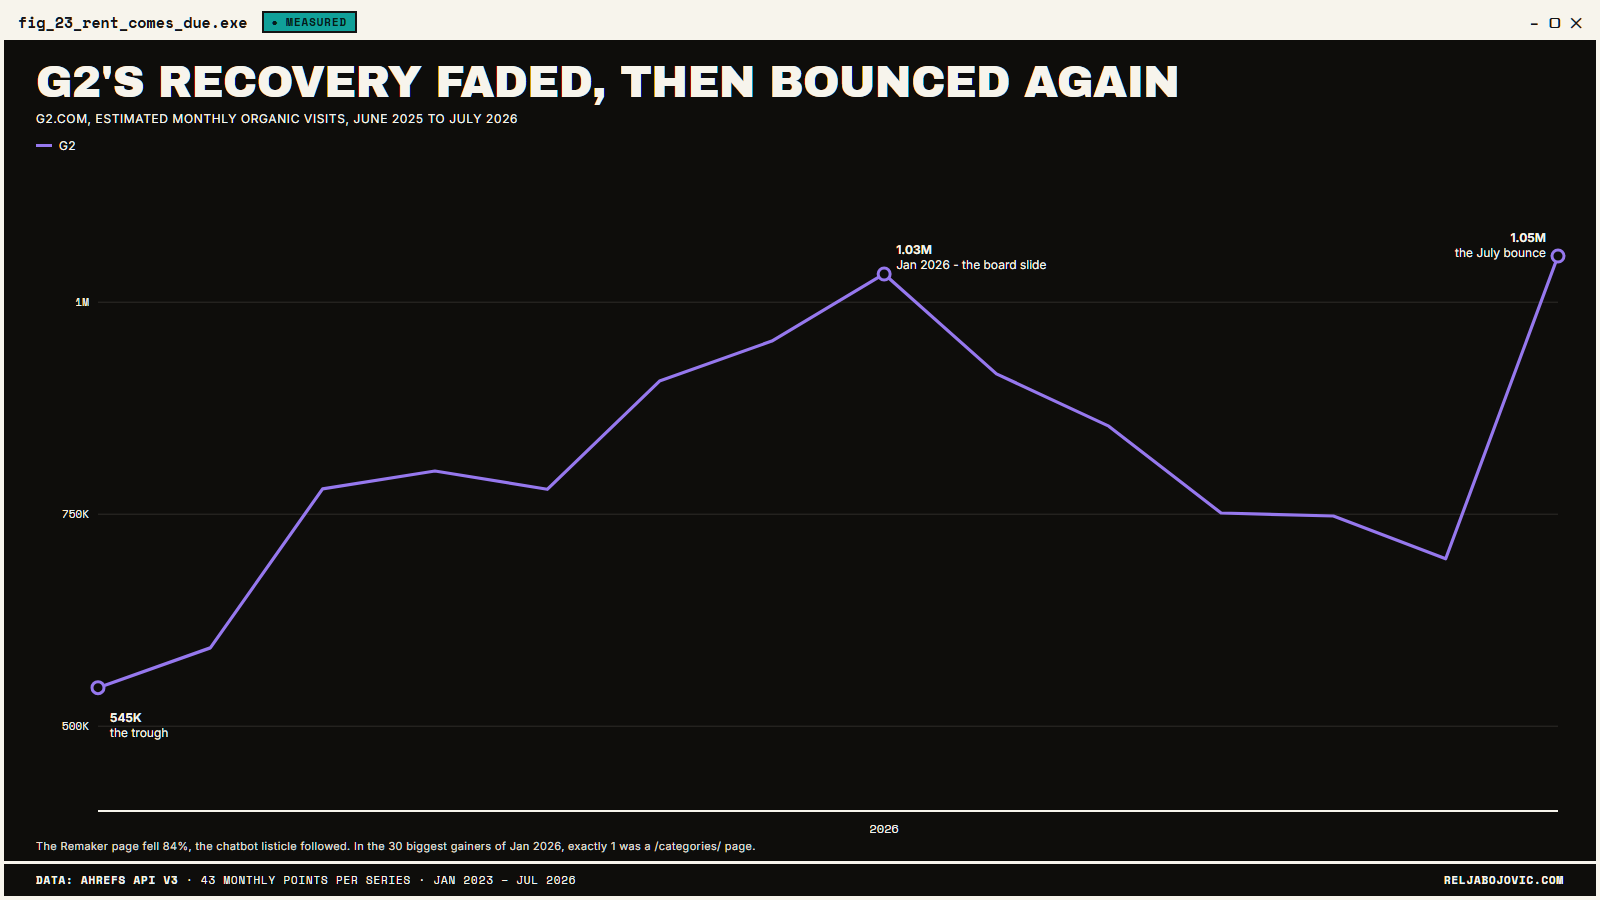
Rented traffic behaves like rent: it stopped. The Remaker page fell 84%, the listicle followed, and the “recovery” faded from 1.03M back to 697K on the same schedule. In G2’s 30 biggest gainers of January 2026, exactly 1 was a /categories/ page - the product G2 actually sells.
Underneath, the core kept rotting: category pages 26,979 visits to 470, -98.3% on the exact pages enterprise vendors pay to look good on. (As of this writing, learn.g2.com still holds 2 AI-sex-chat keywords at position 1. The joke is live and nobody there has noticed.)
The recovery was real on the chart and fictional in the business. If the story ended here, the moral would be “pivot to first-person content and pray.” But it didn’t.
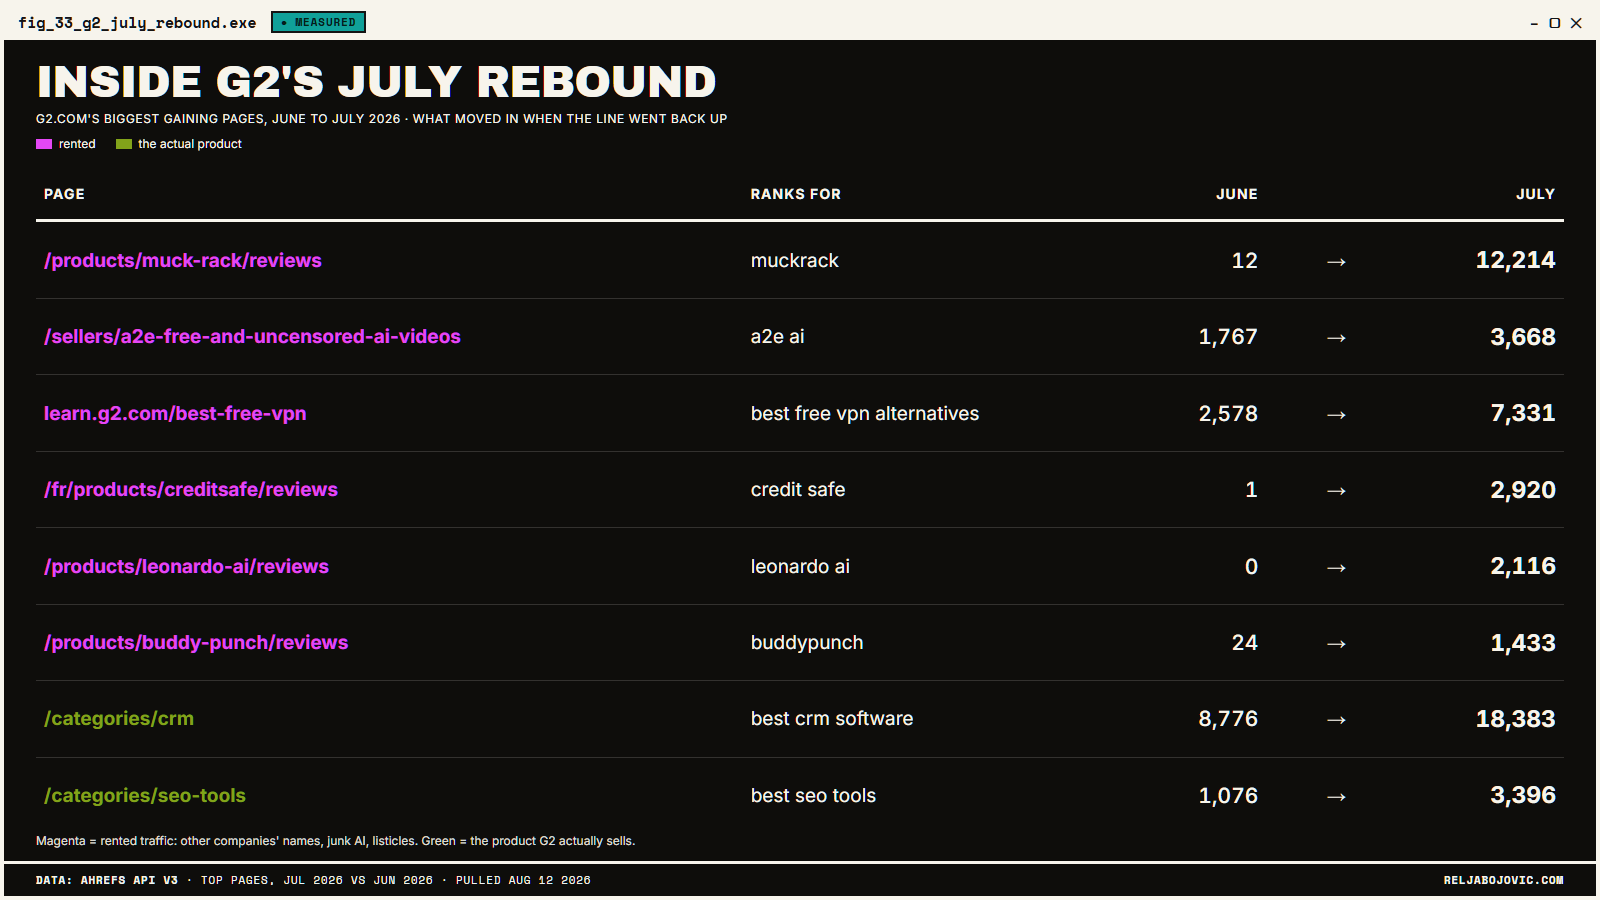
In July 2026, while I was finishing this autopsy, the corpse sat up again: +51% in a single month, back over a million. I opened the drawer expecting one more Remaker and found the whole spectrum of rented keywords side by side.
A Muckrack review page went from 12 visits to 12,214 in 30 days. A seller page called “free and uncensored AI videos” is climbing. The VPN listicles are back, other companies’ brand names are paying the bills again, and somewhere in the middle /categories/crm - the actual product - doubled to 18K, which on this domain counts as a miracle.
Same building, third tenant, same lease terms. If you’re reading this after a couple more G2 “recoveries”, now you know exactly what to check before applauding: not whether the line went up, but who moved in.
The reveal: How Google did it
Read the answer boxes themselves - all 58 of them, sitting on the 5 sites’ own money SERPs - and the whole crime is right there, in descending order.
Boxes where any of the 5 gets cited at all: 14 of 58. Boxes where one of them leads the citation list: 1 - Capterra, “best helpdesk software”, first source in the box, and no blue link anywhere on the page, and not in the organic top 10.
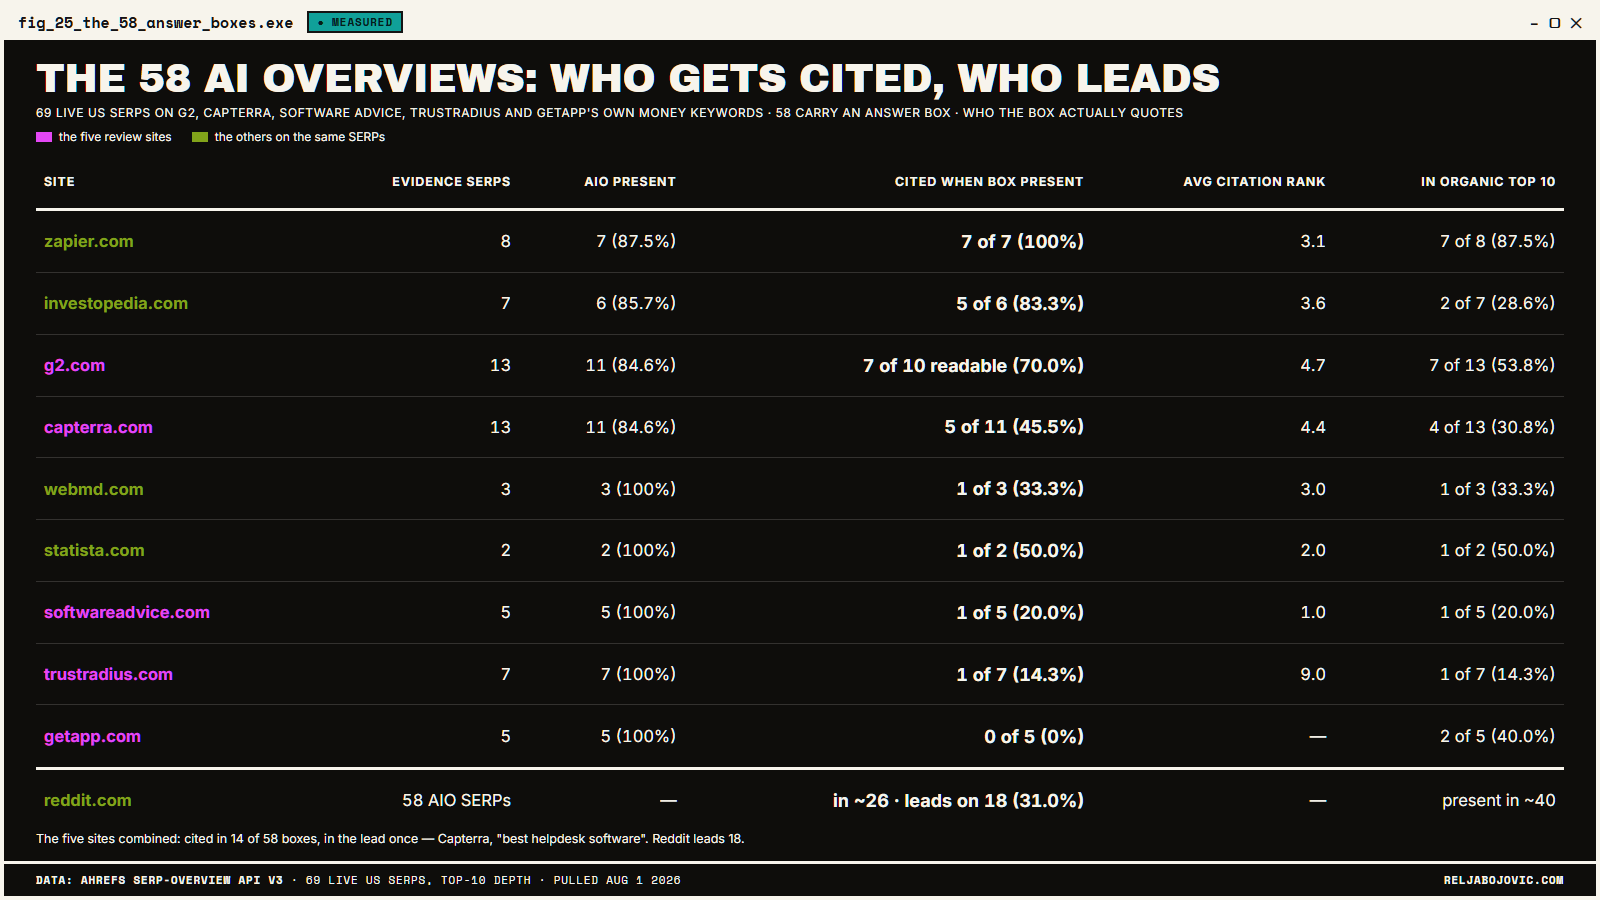
The industry’s best remaining placement on its own turf is being quoted by the thing that replaced it.
Reddit leads 18 times. GetApp appears 0 times - the site that pioneered the genre ended up uncited on its own turf. It’s sad to see 2 decades of structured verdicts got passed over for forum threads and the vendors’ own pricing pages.
So here’s the conclusion, drawn properly: Google vertically integrated the answer business.
- The 2024 policy volley was the demolition permit
- The $60M Reddit deal was the procurement contract
- The SERP features are the new storefront
- And the review industry got cleared out like inventory during a holiday sale
You don’t need a leaked memo from Mountain View when the timeline, the moves, the impact and the devastation left behind all line up.
Run the search yourself
Google “netsuite reviews”. The first source the AI quotes is a Reddit thread titled “Is NetSuite worth it?”. The same thread sits at #2 organic. Capterra’s NetSuite page - maintained, structured, staffed by people with performance reviews - trails a forum post in both layers at once.
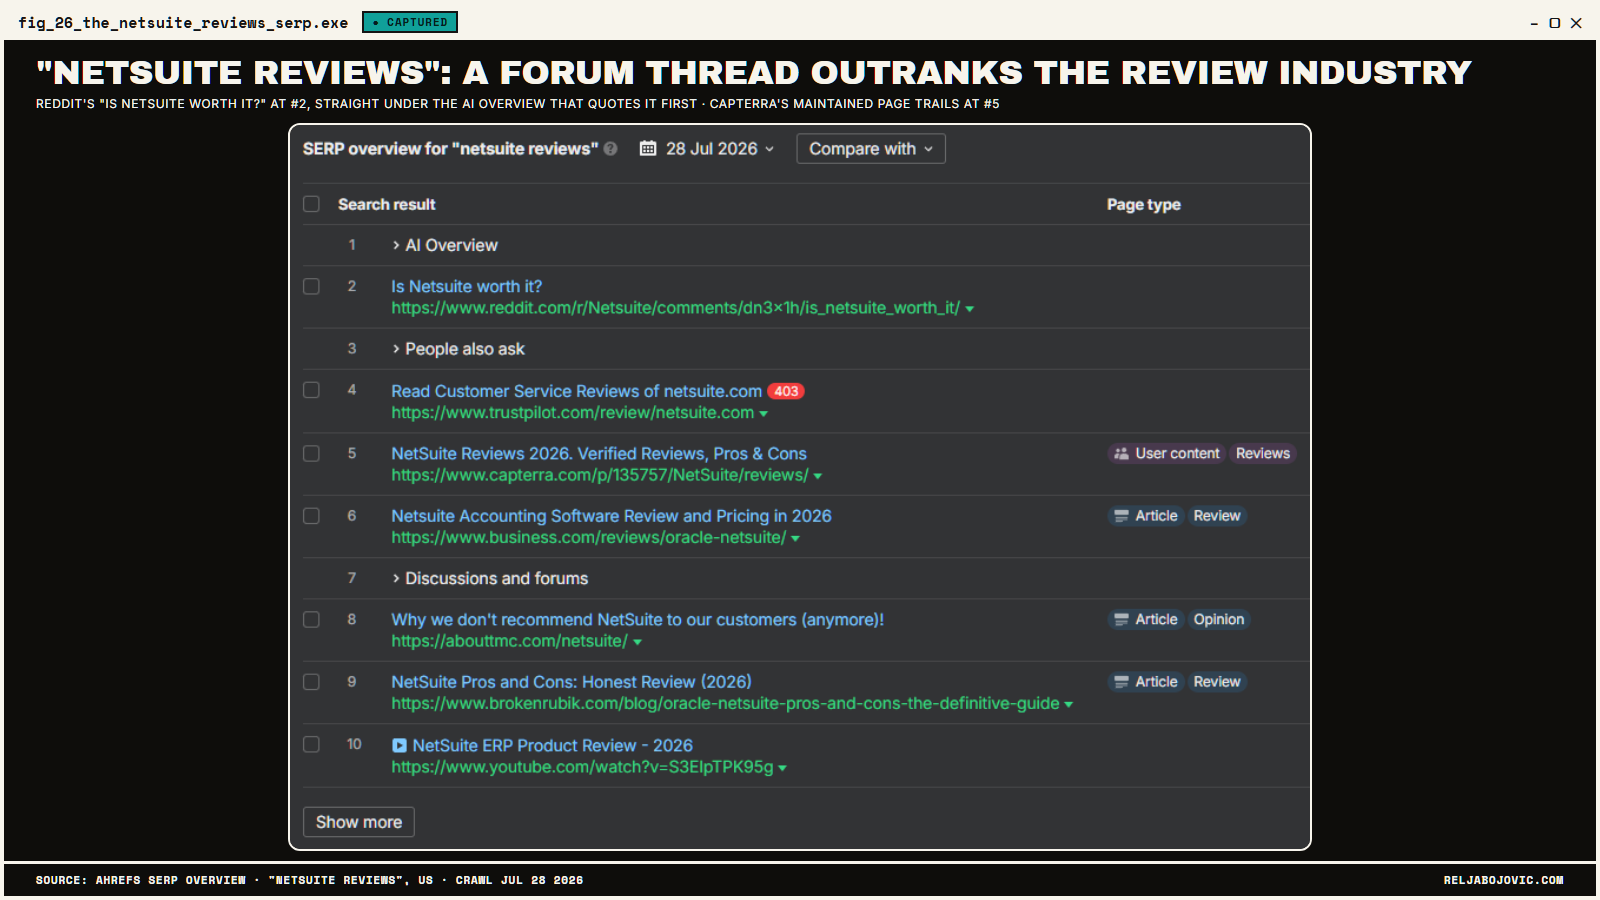
That’s the entire new order in 1 SERP: the crowd above the referee, the box above the crowd, and the referee’s page 3 slots down, holding 2 decades of structured data nobody’s paying for anymore.
Dashboard necromancy
You already know your rank tracker counts an AI Overview citation as position 1 - Semrush documents it, Ahrefs exposes the position type in the API (best_position_kind). What nobody had done is measure what that convention does to a real dashboard during a real collapse.
So I did: across their 40 biggest non-brand keywords each, the 5 sites report 56 top-3 rankings today. 6 exist as blue links, and those 6 are other companies’ brand queries worth about 1,400 visits a month combined.
In August 2024: 10 reported, 4 real. The reported count grew nearly 6x during the exact 2 years they bled out - a rank tracker watching this collapse would’ve reported the hottest streak in company history.
The SERPs without a box
The control group seals the case. The 2 biggest head terms in this study - “accounting software” and “project management software” - carry no AI Overview at all. Funnily enough, on both, the blue links still collect in full: Sage climbed from position 31 and 0 visits to #5 and 13,664 a month after Capterra got demoted off the SERP; project-management.com, DR 72, collects 98,331 a month at #1.
Same industry, same buyers, same year. The only variable deciding whether anyone gets paid is whether the box is standing on the SERP. That’s your killer, and it was never hiding.
Where did the traffic go?
The census first: 46 commercial software SERPs, 344 top-10 organic seats. The 5 review sites hold 13, none higher than #5 - GetApp and TrustRadius hold 0 anywhere. Reddit alone holds 41, 3.2x the entire dead industry. Vendors hold 137.
And the number that buries every comfortable explanation: the winners didn’t win the traffic. The 8 biggest inheritor sites SHRANK during the exact months the giants fell; their growth arrived 15-21 months later and totals 78K monthly visits against 7.63M lost. That’s 1%. Stretch every assumption in their favor: 6%. Even the flagship heir, solutionsreview.com, is itself down 59%, wounded in both kill windows.
Google’s public line through all of this has been that clicks are being redistributed, not destroyed. Nobody had independently checked, so consider this the audit: 1-6% redistributed, the rest gone. Pew’s user-level data explains why - roughly 1% of users click any cited link when a box appears.
As for the conflict of interest this industry existed to referee: Salesforce sits top-5 organic for “best crm software” while the box above it cites a Reddit thread first - a crowd Google pays $60M a year for. Reddit’s curve over this window: 60.8M monthly visits to 1.07 billion.
Follow the money
Gartner’s 3 directories spent an estimated $22.2M on Google Ads across the 43 months of the collapse - $14.56M at Capterra alone, $7.57M in 2024, the cliff year. Capterra now buys 1 visit for every 2 it earns; in January 2023 the ratio was 1 in 6, and its absolute paid volume today is HIGHER than in 2023.
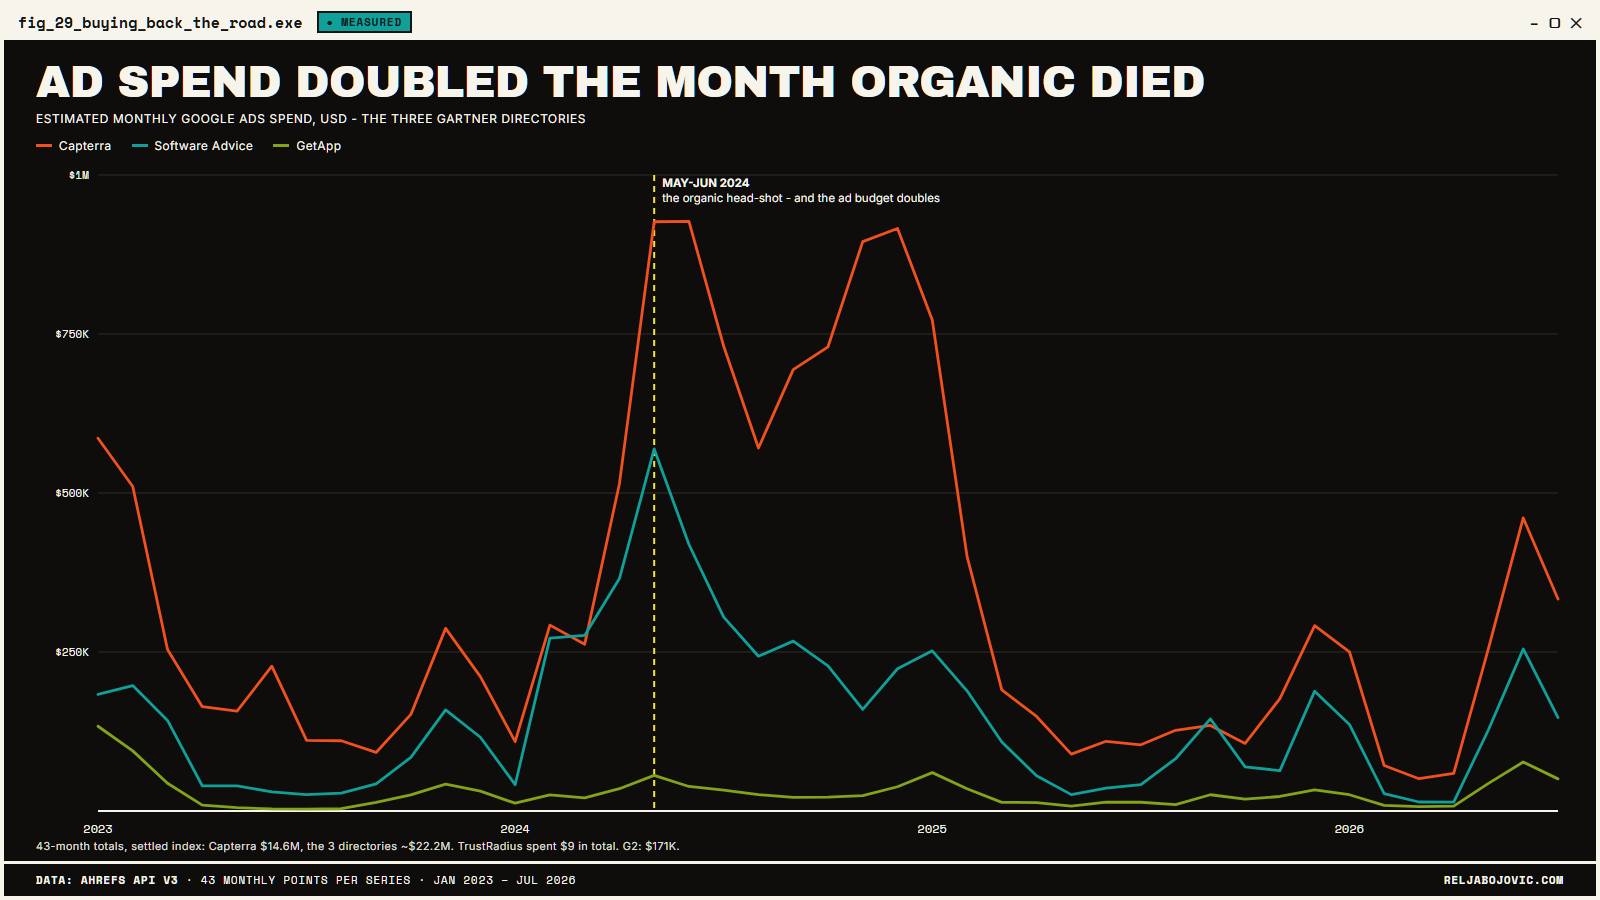
The mechanics deserve a slow read: Google demolished the free road, then sold the corpse a toll pass, and the corpse renews monthly. If you want to know whether the execution was good business, the answer is sitting in the killer’s own till.
TrustRadius spent $9 in 43 months - 9 actual dollars. It never entered the auction, kept its dignity fully intact, and died worst in the set. The market later appraised that dignity as part of a package deal whose press release doesn’t mention traffic.
G2 sits in between at $171K, rounding out yet another interesting convergence between the victim sites. They flashed their wallet in three different ways but ended up cooked in the same stew.
The fire sale
October 2025: Gartner takes a $150M impairment on Digital Markets, citing “ongoing weakness in the market.” 14 weeks later it sells all 3 brands to G2 - the announcement never named a price; the ~$110M surfaced later in Gartner’s own 10-K. G2 was valued at more than $1.1B in 2021, so the last referee standing bought its 3 rivals for roughly a tenth of its own former sticker.
Say what you want about Gartner - I intend to - but they played this correctly and alone: wrote down the damage while its own directories’ dashboards showed rising top-3 counts, sold the corpses to the fourth corpse, and kept the analyst chairs.
The one winning SEO strategy documented in this entire investigation is a well-timed exit. (Credit where due: Mark Barrera flagged the impairment as a distress signal on LinkedIn within days of the deal - the filings and the 5-body data complete the picture he sketched.)
The kicker sits in Gartner’s own house: gartner.com/reviews held its 3 top-10 seats through the whole execution and holds them today, while the 3 directories they sold hold 0 between them. The suits kept their chairs and made off like bandits.
The afterlife: still working, no longer paid
Now the twist: the machines never stopped citing the corpses.
(Snapshot, latest index; no reliable trend series exists for these counts - read levels, not direction.)
ChatGPT cites G2 55,339 times. TrustRadius - 64K monthly visits, organically invisible - gets cited 16,351 times, level with Software Advice. Kevin Indig measured ~35,000 ChatGPT citations: 84% of all review-platform citations go to G2, Capterra, Software Advice and GetApp.
And Google’s own AI quotes G2 12,000+ times while Google organic starved it. There’s a word for extracting ongoing value from an asset while paying its owner nothing, and every SEO reading this used to put it in pitch decks as a compliment.
Even the category’s “survivor” obeys the pattern: SourceForge’s domain line is flat only because its real product is downloads - its review directory, the part that competed with the 5, fell 92.2% on its exact calendar. That dead section now generates 4% of SourceForge’s visits and 70-86% of its AI citations. The machines prefer the corpse.
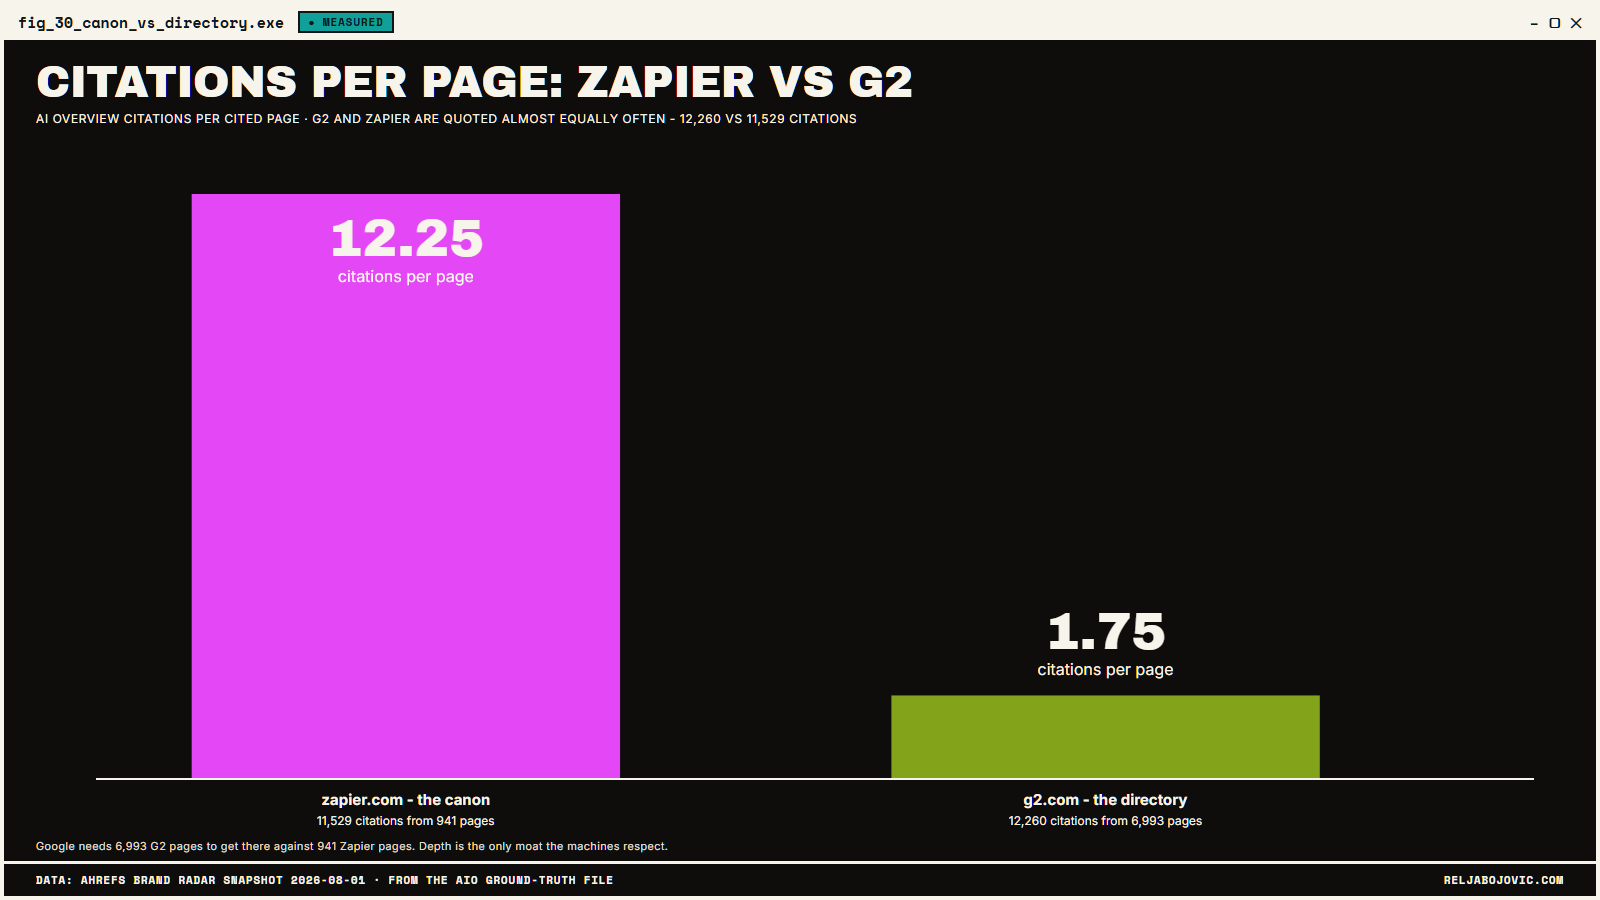
What the machines reward instead is density: Zapier’s citations come from 941 pages at 12.25 each, G2’s from 6,993 pages at 1.75 each. The machines canonize a small library and scrape a big directory for parts - and that ratio, citations per page, is the only strategy-shaped object I found in this entire graveyard.
What’s left of the business
Audit the residue and the 5 sites’ remaining business is 3 items long: standing slightly to the left of other companies’ front doors (26 of Capterra’s top 30 keywords are other brands’ names; TrustRadius lives at #1 for “birdeye pricing”), pricing pages the box occasionally tips, and being quoted by machines for free, forever.
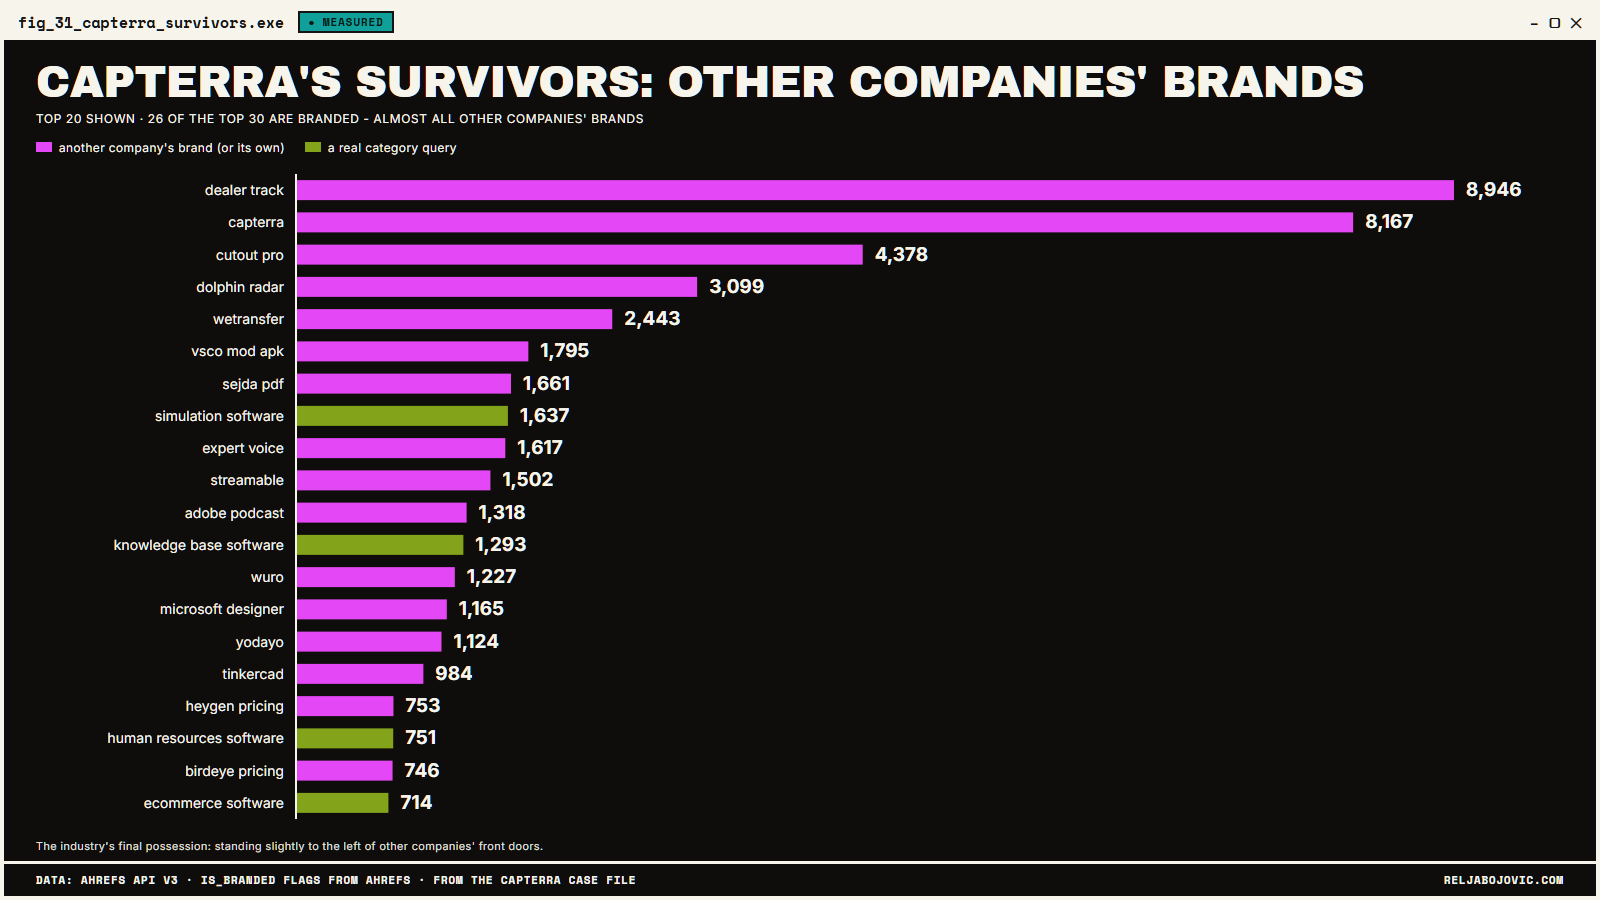
Notice the symmetry, because it’s the whole story in miniature: Software Advice’s first 2023 wound and Capterra’s best 2026 keyword are the same asset class - other people’s brand queries. Google spent 3 years repossessing exactly 1 thing, and the industry’s final possession is the last unclaimed piece of it.
Who’s next: the law, and 3 bets with dates on them
Everything above compresses into 1 rule: a site dies in proportion to how much of its inventory is a question with a settleable answer. “Best X”, “what is X”, “X pricing”, symptoms, definitions - anything that fits in the box. What survives is what the box can’t do: transactions, downloads, tools, brand destinations. Ahrefs’ 300K-keyword study backs it from the other end: 99.2% of AIO-triggering keywords are informational.
The rule already predicts, section by section, who bleeds: PCMag’s review keywords collapsed 66-100% under boxes while its shopping inventory grew inside the same flat domain. RetailMeNot is fine because a coupon is a checkout. NerdWallet (-72.5%) and Healthline (8 straight down months, “spider bite” gone from #1 to not even cited) are already on the conveyor.
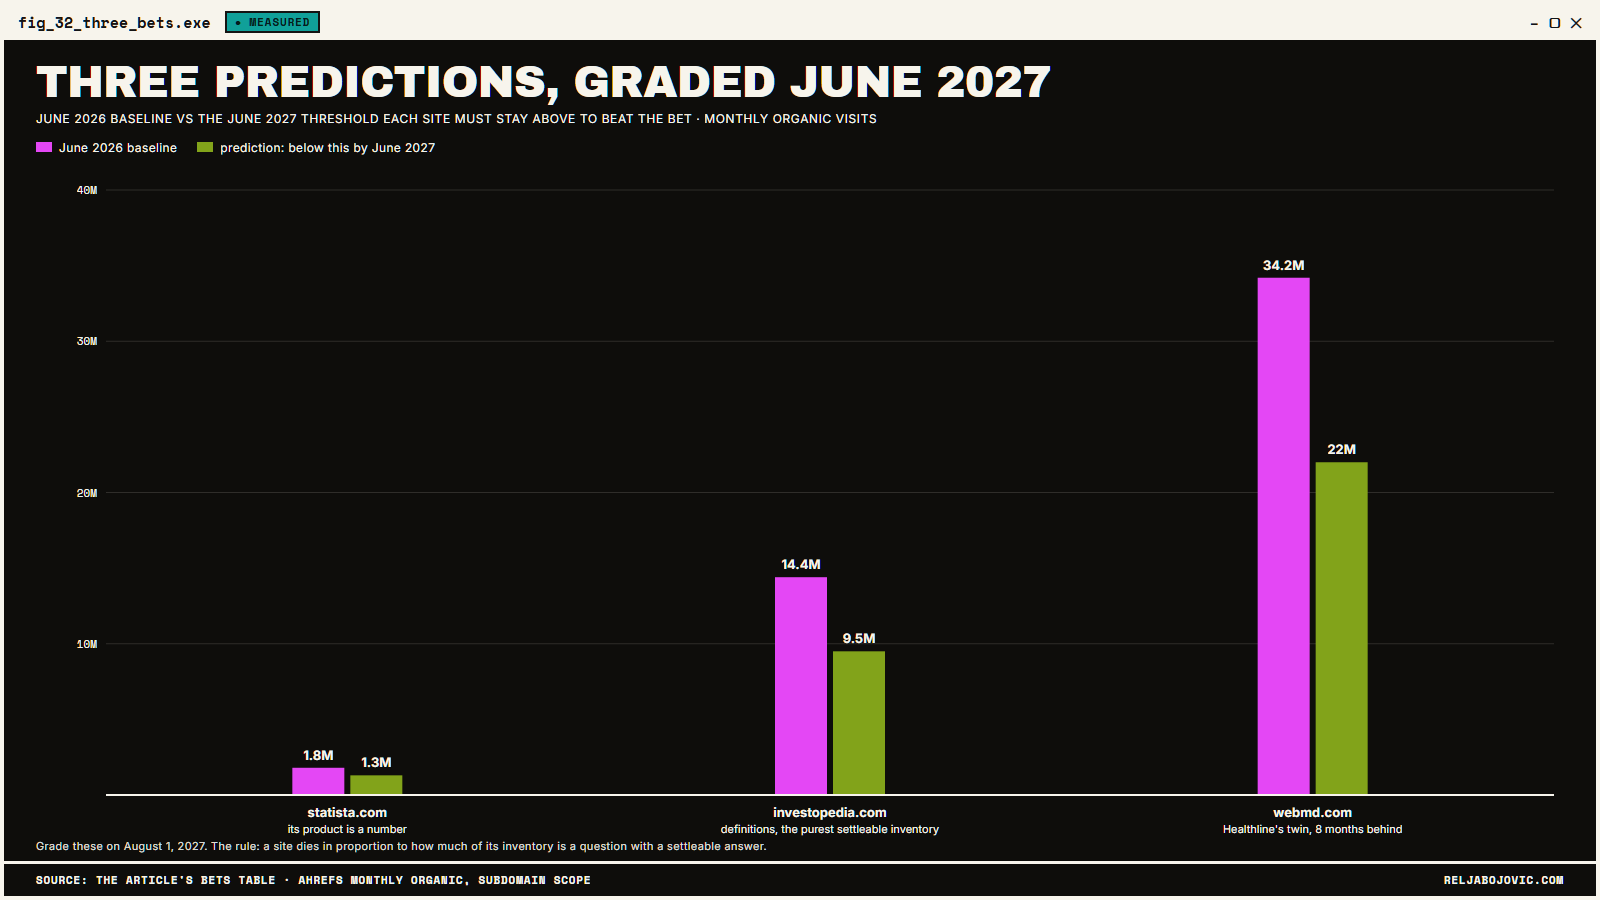
So, 3 bets that can lose. Baselines June 2026, Ahrefs monthly organic, subdomain scope - read this table again on August 1, 2027, and grade me:
| Site | June 2026 baseline | Prediction for June 2027 | Why |
|---|---|---|---|
| statista.com | 1,775,708 | below 1,300,000 | its entire product is a number, and a number fits in a box |
| investopedia.com | 14,422,481 | below 9,500,000 | the purest settleable inventory on the internet: definitions |
| webmd.com | 34,221,155 | below 22,000,000 | Healthline’s twin, 8 months behind on the same conveyor |
(Pre-empting the 2 obvious replies: yes, Investopedia licenses content to OpenAI for a reported $16M+ a year - that’s what surviving the loss of search looks like, and it doesn’t put a click back. And these bets price search inventory, not company survival.)
The scalpel
The same audit on your own site, 20 minutes:
-
Pull your keywords ranking 1-3 today, with traffic now and 18-24 months ago.
-
Filter to real organic positions.
-
Keep the ones where position held but traffic fell more than 60%.
-
Check those SERPs for a box, by hand.
-
Sum the lost clicks - that’s what got answered away rather than outranked, and no amount of better SEO buys it back.
Your dashboard won’t show you this number. That’s why I’m giving you the steps.
Method
- Traffic, keyword and page data pulled July 30 - August 12, 2026: Ahrefs API v3 - 43 months per domain, subdomain scope, refreshed in full against the live index at publication, August 2026
- AI citation counts: Ahrefs Brand Radar, latest index
- Live verification: every present-tense SERP claim checked by hand, US, the week before publication
- Financials: Gartner’s SEC filings and the companies’ own announcements
- Google update dates: Search Status Dashboard
- Excluded as known Ahrefs index artifacts: post-Sep-2025 tail counts, imputed volume series, partial final months
The close
I know it’s not pretty, but this is what happens when your whole brand settles for being a middleman. For years, it was easy work and copious amounts of affiliate revenue, but the end had to come sooner than later.
All five of the victims lived off BOFU queries. But overnight, all those queries could be answered by a single glance at an AI overview or reply from Claude.
So, should you be scared that Google is going to go all Slenderman on your site? If what you’re providing to visitors is accessible, clear, and tangible, no. If you’re regurgitating information and doing it WORSE than LLMs, then I’d suggest you start flipping the whole company and doing a Gartner.